On Thanksgiving, My Parents Admitted They Sold My $32,000 Harley and Emptied My $14,000
On Thanksgiving, My Parents Admitted They Sold My $32,000 Harley and Emptied My $14,000 Savings for My Sister’s House—Then Mom Said, “Co-sign Her Mortgage or Leave Tonight.” I Chose the Door, but the Note I Left Behind Exposed Three Years of Family Money—and by Morning, My Sister’s Closing Was Falling Apart for a Reason She Never Expected.
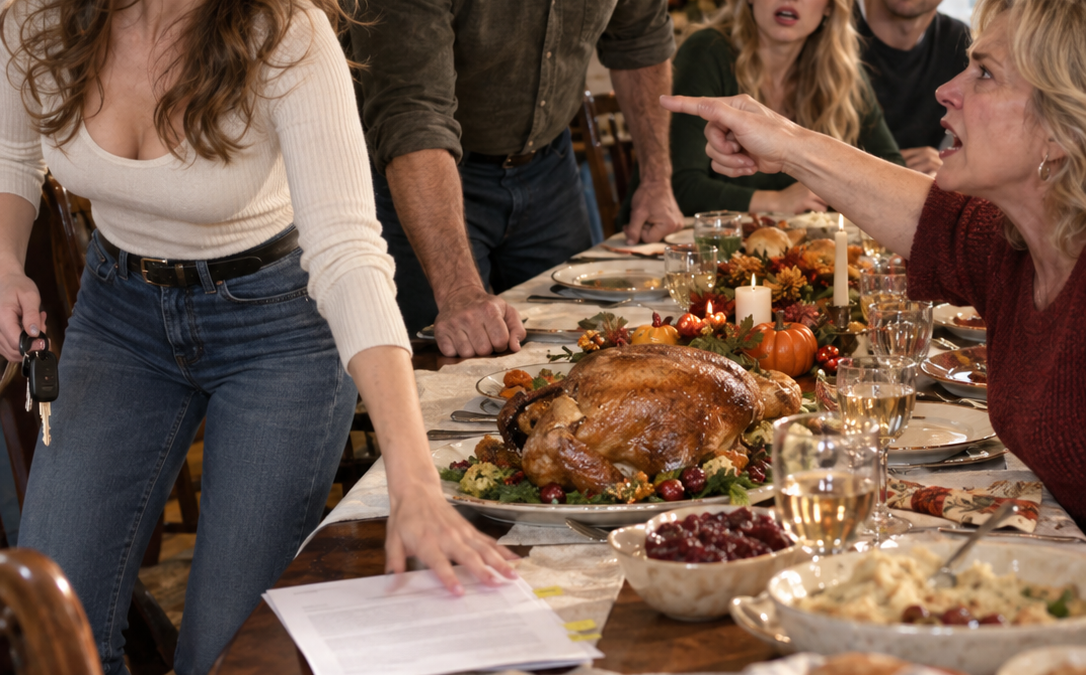
The mortgage form was sitting beside my Thanksgiving plate before anyone said a word about my motorcycle.
Three yellow tabs marked the places where I was supposed to sign. My mother had laid a black ballpoint pen across the top as neatly as she had arranged the silverware, while turkey steamed in the center of the table and cranberry sauce gleamed in the crystal bowl she only brought out for holidays.
Then my father looked at me and said, “We sold the Harley this morning.”
For a second, I thought I had misunderstood him.
My name is Brier. I was twenty-eight, a union CNC machinist at a precision manufacturing plant, and I had spent five years learning to cut steel to tolerances measured in thousandths of an inch. My work rewarded accuracy. A measurement was either right or wrong.
My family had always been harder to measure.
Dad—Doyle—sat at the head of the table with the carving knife beside him. My mother, Mavis, sat to his left. Across from me were my younger sister Harper and her boyfriend, Nico.
Nobody looked surprised.
That was the first thing that told me this wasn’t an impulsive decision.
Three years earlier, I had bought that Harley with $32,000 I saved myself. I worked overtime, skipped trips, packed lunches, and kept my old Honda Civic instead of trading it because I wanted a backup vehicle.
The motorcycle wasn’t something my parents bought me. It wasn’t a family possession. It represented two years of deliberately saying no to other things because I wanted one thing that was mine.
There was only one problem.
The title was in Doyle’s name.
At the time, it had seemed like paperwork. I trusted my father. I never imagined I would need protection from him.
Now he was carving turkey while explaining that a dealership buyer had come that morning with a cashier’s check for $32,000.
“The money is already in Harper’s escrow account,” he said.
Harper and Nico were trying to buy a three-bedroom house on Weller Road for $245,000. They had a financing gap, and apparently my motorcycle had become the solution.
I stared at Harper.
“You knew?”
She didn’t answer immediately.
Nico tore a dinner roll apart with his thumbs.
That tiny movement bothered me more than yelling would have. Everyone was behaving as if this conversation had already happened and I was simply the last person invited to it.
Then Doyle added, “And your emergency fund.”
I turned toward him.
“What about it?”
“That account still had my name on it. I withdrew the money in August.”
Fourteen thousand dollars.
My emergency savings.
Gone for three months.
“You never even noticed,” he said. “That should tell you how much you actually needed it.”
I remember looking at my mother because some part of me still expected her to interrupt him.
She didn’t.
The account had been opened when I was seventeen, with Doyle attached to it. I had never removed him because I had never believed my father would empty it behind my back.
August.
He had taken the money in August and spent three months asking about my work, eating Sunday dinners with me, and acting as if nothing had changed.
Then Doyle leaned back.
“You’re twenty-eight, Brier. No boyfriend. No house. No plan past your next paycheck. Harper has Nico. She’s building a future. You have a motorcycle and money sitting in an account.”
That was when I understood why the mortgage form was beside my plate.
The $46,000 wasn’t enough.
They wanted my credit too.
My score was around 760. Harper’s wasn’t strong enough for the loan she wanted, and Nico couldn’t carry it either.
Mavis slid the form closer.
“Co-sign it,” she said, “or pack your bags tonight.”
I lived in my childhood bedroom, but I hadn’t been living there for free.
For three years, I had transferred $750 every month toward my parents’ mortgage. I covered about $280 in utilities. I paid Harper’s $180 monthly car insurance. I had helped with property taxes and loaned Harper another $8,200 that somehow never came back.
Nobody at that table mentioned any of that.
Instead, Mavis looked at me and said, “Your sister is building a home. You’re building nothing.”
Harper leaned forward.
“You weren’t going to use that money for anything real anyway. You just liked watching the number go up.”
I looked down at the mortgage papers.
Thirty years.
That was what they wanted from me.
If Harper and Nico stopped paying, their problem would become mine. Their missed payments would hit my credit. Their mortgage could interfere with my ability to finance a home of my own.
My coworker Sage had once described co-signing perfectly after a relative asked her to do it.
“You become the floor under somebody else’s house. If the floor cracks, you’re the one falling through.”
My fingers were inches from the pen.
Then I thought about the Harley key.
Two weeks earlier, I had used the family computer to print a shipping label. Harper had left her email open.
I hadn’t gone looking for anything.
But the subject line “house stuff” caught my attention because it was addressed to Doyle.
I opened it.
Harper had written:
“Dad, can you get the rest from Brier’s fund? The motorcycle should cover the gap. She doesn’t need it if she stays here.”
I read that sentence several times.
She doesn’t need it if she stays here.
Suddenly, every time my mother had told me, “The family needs you close,” sounded different.
Close had never meant loved.
Close meant available.
I checked my emergency account immediately.
Zero.
The $14,000 withdrawal had happened August 14.
I didn’t confront anyone.
Instead, I met Sage after our shift and told her everything.
She listened beside her truck in the cold parking lot, arms crossed, safety glasses pushed into her hair.
When I finished, she asked one question.
“How much have you given them?”
I had already calculated it.
Three years of mortgage help: $27,000.
Utilities: $10,080.
Harper’s insurance: $6,480.
Property taxes: roughly $11,400.
Harper’s unpaid loans: $8,200.
About $63,160 before the motorcycle and savings.
Sage stared at me.
“Sixty-three thousand dollars of support,” she said. “Then forty-six thousand more they took without asking.”
She shook her head.
“Brier, you’ve been underreacting for three years.”
That sentence followed me home.
Ten days before Thanksgiving, I met with an attorney named Quinton. I brought bank statements, purchase records, transfers, and everything I had showing where the Harley money originally came from.
He explained that because Doyle held the motorcycle title, the sale itself was complicated, but my documented payments gave me a potential civil claim. The savings account was also legally accessible to Doyle because his name remained attached, but using the funds for Harper could still create a separate civil dispute.
Quinton began preparing a $46,000 demand.
Then I learned something else.
Harper’s $8,200 in “loans” hadn’t gone toward the emergencies she described.
She had used much of it to reduce credit-card balances and improve her credit profile before applying for the mortgage.
My money had been helping build her house plan long before anyone put papers beside my Thanksgiving plate.
Five days before dinner, I sat at my workbench during lunch and wrote every number on a yellow legal pad.
Mortgage.
Utilities.
Insurance.
Taxes.
Loans.
Motorcycle.
Savings.
At the bottom, I wrote one sentence:
“I was not your daughter. I was your payment schedule.”
I folded the paper once and put it inside my jacket.
So when Mavis pushed that mortgage form toward me on Thanksgiving and said, “Sign it or leave,” I already knew what I was going to do.
I didn’t yell.
I didn’t throw the papers.
I pushed my chair away from the table and walked through the kitchen toward the garage.
The Harley was gone.
But the key was still hanging from the little hook beside the door.
Doyle hadn’t taken it because it was worthless without the motorcycle.
I removed it.
The steel ring felt strangely heavy in my palm.
A key without a bike starts nothing.
I walked back through the kitchen.
Harper watched me.
Mavis said, “Where are you going?”
I reached inside my jacket, removed the folded note, and placed it face down on the counter.
Then I picked up my duffel bag.
Doyle finally raised his voice.
“Brier, don’t be ridiculous.”
I looked at the mortgage form beside my untouched Thanksgiving plate.
For three years, I had thought I was helping my family stay afloat.
Now I knew they had built their entire financial plan around the assumption that I would never stop.
I put the useless motorcycle key in my pocket.
Then I walked out.
That night, I slept on Sage’s couch.
At 8:15 the next morning, Harper arrived at my parents’ house expecting to discuss the closing schedule for Weller Road.
She found my folded note on the kitchen counter.
She opened it casually at first.
Then she reached the numbers.
Her expression changed.
By the time she reached the final sentence, she was holding the paper with both hands.
Minutes later, she was pacing the kitchen with the escrow company on the phone.
Without my signature, her mortgage couldn’t proceed under the financing arrangement she had.
Mavis grabbed another phone and called about my parents’ own December mortgage.
The automatic $750 payment I had made every month for three years was no longer coming.
And Doyle?
He didn’t call anyone.
He stood at the counter holding my note.
His eyes stopped on the last line.
“I was not your daughter. I was your payment schedule.”
He read it again.
Then again.
For the first time, the people who had spent years treating my paycheck like part of the household budget were being forced to calculate what happened when the person attached to that paycheck simply walked away.
And while Harper was demanding answers from the lender and my mother was asking the bank what happened to December’s payment, I was sitting across town opening a new account with one name on it.
Mine.
📖 The story isn’t over yet—there’s still more to come! 💝
🚨 All characters and events in this story are entirely fictional. Please do not imitate or recreate them in real life. 🤫🤫🤫
On Thanksgiving, the mortgage form was already sitting beside my plate when my father told me he’d sold my $32,000 Harley. Before I could fully understand that sentence, he calmly admitted he’d also emptied my $14,000 emergency fund three months earlier. Nobody at the table looked surprised.
Then my mother pushed the papers toward me and said, “Co-sign Harper’s house or pack your bags tonight.” My younger sister watched from across the turkey while her boyfriend tore apart a dinner roll. I remember thinking that whatever happened next had been planned long before I sat down.
What they didn’t know was that I had discovered part of that plan two weeks earlier. There was a folded note inside my jacket, an attorney preparing a demand letter, and one sentence my father would soon read until his hands shook. The only question left was whether I would actually have the nerve to walk away.
My name is Brier, and at twenty-eight I worked as a CNC machinist at a precision manufacturing plant. Five years in a union position had taught me to trust measurements more than promises. Steel doesn’t care about your intentions; either the dimensions are right or the part fails inspection.
The Harley had been one of the few things in my life I bought simply because I wanted it. I saved $32,000 over two years by taking overtime, skipping vacations, carrying lunches to work, and keeping my ten-year-old Honda Civic instead of upgrading it.
Because of a paperwork decision I had once considered harmless, the title was in my father’s name.
Doyle was fifty-six and worked as an auto-body-shop foreman. His hands carried grease in the lines of his knuckles even after he scrubbed them. Growing up, I thought of those hands as dependable.
My mother, Mavis, worked part-time at a bakery counter. My younger sister Harper was twenty-five and worked part-time as a barista. Her boyfriend, Nico, worked in a warehouse.
Harper and Nico wanted a $245,000 three-bedroom house on Weller Road.
They had the dream.
They didn’t have the numbers.
For years, I had been the person who fixed numbers.
When my parents struggled with their mortgage, I started contributing $750 each month. Then came utilities. Harper’s car insurance. Property taxes. Small emergencies that were never small once they reached my phone.
Mavis would always say the same thing.
“The family needs you close.”
I lived in my childhood bedroom and told myself the arrangement was fair. They gave me a roof; I helped with expenses. I didn’t stop to ask why my help kept increasing while everyone treated my presence as evidence that I wasn’t moving forward.
Harper borrowed $3,200 once and promised repayment after her hours increased.
Nothing came back.
Later she needed $5,000 for what she described as car trouble and other bills.
Nothing came back then either.
Still, I kept helping.
The moment everything changed began two weeks before Thanksgiving when I used the family desktop to print a shipping label. Harper had left her email logged in.
A sent message to Doyle carried the subject line “house stuff.”
I opened it.
“Dad, can you get the rest from Brier’s fund? The motorcycle should cover the gap. She doesn’t need it if she stays here.”
I read the sentence twice.
Then I opened my banking app.
My emergency fund showed zero.
The withdrawal history said $14,000 had left on August 14.
Three months earlier.
I sat motionless at the computer while memories began rearranging themselves.
Doyle asking whether I wanted anything from the hardware store.
Mavis reminding me about Sunday dinner.
Harper complaining about mortgage rates.
All of them had known my savings were gone while I didn’t.
I closed the browser and said nothing.
After work, I met my coworker Sage in the plant parking lot.
Sage was the kind of person who could rebuild a truck and argue with a supervisor about torque calculations in the same afternoon. When I finished explaining everything, she didn’t offer comfort first.
She asked for numbers.
So I gave them to her.
Thirty-six months at $750 toward the mortgage: $27,000.
Utilities averaged $280 a month: $10,080.
Harper’s insurance: $6,480.
Property taxes over three years: about $11,400.
Harper’s unpaid borrowing: $8,200.
Roughly $63,160 in support.
Then the $14,000 disappeared.
And Harper was suggesting Doyle sell my $32,000 motorcycle.
Sage stared across the dark parking lot.
“You’ve underreacted for three years.”
Ten days before Thanksgiving, I sat in attorney Quinton’s office with my records spread across his desk.
He explained that Doyle’s name on the motorcycle title made the sale legally complicated, but my documented purchase payments gave me grounds to pursue a civil claim. The joint savings account was another difficult issue because Doyle had withdrawal authority, yet the use of my funds for Harper’s benefit could still be challenged.
Quinton prepared a demand for $46,000.
Then my records revealed something I hadn’t expected.
The money Harper borrowed had largely gone toward reducing credit-card balances.
She hadn’t simply been surviving.
She had been improving her financial profile for the mortgage.
My money had been part of her house plan before I knew there was a house plan.
Five days before Thanksgiving, I sat at my workbench during lunch and wrote every amount on yellow legal paper.
At the bottom, my pencil stopped for a moment.
Then I wrote:
“I was not your daughter. I was your payment schedule.”
I folded the note once.
On Thanksgiving, it was still inside my jacket when Doyle announced the Harley was gone.
“The dealership buyer paid thirty-two thousand,” he said. “It’s already been deposited toward Harper’s house.”
I looked across the table.
Harper didn’t deny knowing.
Then Doyle told me about the savings.
“You didn’t notice for three months,” he said. “That proves you didn’t need it.”
Mavis pushed the mortgage form closer.
“Co-sign it or leave tonight.”
Harper added, “I need a roof. You need a reality check.”
My hand moved toward the pen.
For one terrifying second, habit nearly won.
Then I thought about Sage.
You underreacted for three years.
I stood.
I walked into the garage and found the motorcycle hook empty except for the key Doyle had left behind.
I took it down.
When I returned to the kitchen, I placed my folded note on the counter.
Doyle frowned.
“What’s that?”
“You’ll figure it out.”
I picked up my bag.
Mavis stared at me.
“You’re seriously leaving over this?”
I looked at the mortgage papers.
“No. I’m leaving because you expected me not to.”
Then I walked out.
Chapter 2 — The Note Turned Their Holiday Victory Into Financial Panic Overnight
Sage opened her apartment door that night wearing flannel pajama pants and an old work shirt. She looked at my duffel bag, then at my face.
“Coffee or water?”
That was all she asked.
Ten minutes later, two mugs of instant coffee sat on her table. My useless motorcycle key rested beside mine.
I asked her the question that had been chewing at me since I left.
“Did I overreact?”
Sage looked genuinely confused.
“Brier, they sold your bike, emptied your savings, and tried to tie your credit to a thirty-year mortgage. Leaving was the first normal reaction you’ve had.”
I slept badly but woke without regretting it.
Friday morning, Harper arrived at my parents’ house around eight.
She found the note.
The first lines were numbers.
Mortgage contributions.
Utilities.
Insurance.
Taxes.
Loans.
Then the Harley.
Then the savings.
At the bottom:
“I was not your daughter. I was your payment schedule.”
Harper called the escrow company immediately.
Her financing required a qualified guarantor. Her credit score was around 640. Nico’s was closer to 610.
Mine was 760.
Without my executed signature, the lender wouldn’t finalize the arrangement they had built.
Harper demanded alternatives.
The escrow officer told her she could find another qualified co-signer or reapply under different terms.
There wasn’t another co-signer.
Meanwhile, Mavis called about my parents’ mortgage.
For three years, $750 had automatically arrived from my account every month.
I had canceled it.
The next payment would be Doyle and Mavis’s responsibility.
Nobody could accuse me of stealing their money.
I simply stopped giving them mine.
While their kitchen filled with phone calls, I was sitting inside Marsh Avenue Credit Union.
The teller asked whether I wanted a joint holder.
“No.”
I deposited $1,200 from my latest paycheck.
For the first time since I was seventeen, every dollar in my savings account belonged to an account with only my name attached.
Five days later, I signed a lease on a five-hundred-square-foot studio three miles from the plant.
It wasn’t impressive.
The stove clicked before lighting. The walls were bare. My mattress sat on a cheap metal frame.
But the lease had one name.
Brier.
The key to that apartment opened something.
The Harley key in my jacket didn’t.
For several nights, I kept both anyway.
Chapter 3 — My Father Came For Me And Found An Invoice
Ten days after Thanksgiving, somebody knocked hard on my studio door.
Doyle stood outside in his work jacket.
“Come home,” he said. “Your mother misses you.”
He looked past me at the apartment as though the bare walls proved I had made a mistake.
I let him inside.
There was only one chair, so he took it. I remained standing.
Then I removed the Harley key from my pocket and placed it on the table.
“That key starts nothing now.”
His eyes dropped to it.
“You said I had no plan beyond my next paycheck,” I continued. “My paychecks paid part of your mortgage for three years. Your plan was my paycheck.”
His jaw tightened.
So I gave him the measurements.
“Twenty-seven thousand toward the mortgage. Ten thousand eighty in utilities. Six thousand four hundred eighty for Harper’s insurance. Eleven thousand four hundred in property taxes. Eight thousand two hundred Harper borrowed and never repaid.”
Doyle shifted.
“Families help each other.”
“I did help.”
I leaned against the table.
“Sixty-three thousand one hundred sixty dollars of help.”
He said nothing.
“Then fourteen thousand from my savings. Thirty-two thousand from my motorcycle.”
I watched his expression.
“You didn’t ask me because you knew the answer would be no.”
Doyle rubbed both hands across his thighs.
“Harper needed stability.”
“So did I.”
“She has Nico. They’re trying to build something.”
“And you decided that meant I wasn’t.”
He started talking about the house I grew up in and everything he had provided when I was a child.
I didn’t argue with that.
Instead, I said, “Quinton mailed you a certified demand.”
His face changed.
“Who?”
“My attorney.”
The demand sought $46,000 related to the Harley and savings.
“You got a lawyer against your own father?”
“No. I got a lawyer for myself.”
That distinction silenced him.
His eyes moved back to the key.
For years, Doyle’s authority had worked because I accepted the premise underneath it: he was my father, therefore his judgment outranked my boundaries.
Sitting in my apartment, I realized that premise had expired.
“This is the last time you come here asking me to return to the old arrangement,” I said.
His shoulders dropped slightly.
“Your grandfather built that garage. That hook has been there since before you were born. Family is bigger than a motorcycle.”
“You’re right.”
He looked at me.
“It was never about the motorcycle.”
I opened the door.
He stood in the hallway for several seconds before leaving.
I locked the deadbolt behind him.
The click was quiet.
It sounded better than any argument I could have won.
Chapter 4 — Once My Money Stopped, Everyone Finally Saw The Arrangement
Four days later, my uncle Ty called.
Ty was Doyle’s older brother and owned a plumbing business. He had heard from relatives that I had abandoned Thanksgiving over a “disagreement about Harper’s house.”
He asked for my version.
I gave him numbers.
Ty didn’t interrupt.
When I finished, he was silent.
“Give me an hour.”
He called Doyle.
Later, Ty told me exactly what he’d said.
“You sold the motorcycle she paid for, emptied her savings, then put a mortgage guarantee beside her Thanksgiving dinner?”
Doyle tried explaining that Harper needed help.
Ty stopped him.
“My wife sent Christmas invitations this morning. Yours isn’t coming. Brier’s is. She’s bringing dessert.”
For the first time, somebody inside the family treated what happened as more than a disagreement.
The next morning, Mavis called.
Her voice was unusually soft.
“Your father isn’t doing well. His blood pressure is high. He hasn’t slept.”
I closed my eyes.
For years, that tone could make me move before I thought.
“Come home for an hour,” she said. “Whatever you wrote on that note broke something in him.”
“What I wrote was a list of payments.”
“He’s your father.”
“And Harper is your daughter. Call her when you need help.”
Silence.
The guilt hit after I hung up.
I almost called back.
Instead, I set the phone down.
At my parents’ house, the bills were beginning to expose exactly what my contributions had covered.
Their mortgage payment was $1,840.
Utilities averaged $280.
Property taxes added another regular burden.
Doyle had a truck payment.
Harper’s car insurance had also depended on me.
When I stopped paying it, the policy eventually lapsed.
Harper called Doyle furious after receiving the cancellation notice.
“Why didn’t anybody tell me?”
Doyle had to answer with five words.
“Brier was paying for it.”
Harper went silent.
She had spent years describing me as someone who wasn’t building a life.
Now parts of hers were shutting off because I had stopped financing them.
The Weller Road purchase was also deteriorating.
The mortgage preapproval had an expiration date.
Without my signature, the clock kept moving.
The $46,000 from the Harley and savings sat tied to a house transaction that could not close under the planned financing.
For the first time, everyone had money sitting in front of them and still couldn’t make the numbers work.
That had always been my role.
I had been the missing number.
Now I was gone.
Chapter 5 — The House Deal Collapsed While My Boundaries Became Permanent
Near the end of December, Harper and Nico sat in a title-company conference room with a closing agent.
The mortgage approval had expired.
Without a qualified co-signer, the lender wouldn’t extend the arrangement as planned.
The closing agent shut the file.
Harper stared at the folder.
Inside were house keys she had expected to receive.
They stayed there.
The Weller Road property would return to the market.
Harper and Nico eventually rented a one-bedroom apartment for $1,200 a month.
There was an ugly irony in that number. Their rent was higher than the mortgage payment they had imagined paying, but a lender’s decision wasn’t based on what Harper believed she deserved.
It was based on whether the numbers worked.
They didn’t.
At my parents’ house, Quinton’s demand letter sat beside mortgage statements and overdue household obligations.
Doyle didn’t respond before Christmas.
Quinton prepared for the next step.
I didn’t celebrate any of it.
That surprised me.
For weeks, I had imagined that seeing consequences would feel like justice.
Mostly it felt quiet.
Sage and I worked overtime the Saturday after Christmas.
During lunch, she noticed me checking my banking app.
“How bad?”
“Two thousand eight hundred.”
She nodded.
“Better than zero.”
It was.
My new account was rebuilding slowly. Rent was $850. I still drove the Civic.
The Harley was gone.
Some nights I opened the drawer where I kept its key.
I never threw it away.
I also stopped carrying it.
That distinction mattered.
The key no longer needed to remind me to stay angry.
It had become evidence of a lesson I already understood.
Meanwhile, relatives began hearing the full version of Thanksgiving.
Some called.
Some didn’t.
A few clearly thought involving an attorney went too far.
I stopped trying to persuade them.
That was another new boundary.
I had spent years believing that being understood was necessary before I was allowed to protect myself.
It wasn’t.
I didn’t need a unanimous family vote.
I needed my own consent.
And they no longer had it.
Chapter 6 — Harper’s Email Revealed Who Had Planned Everything From Beginning
The deeper truth wasn’t that Doyle had made one terrible Thanksgiving decision.
It was that Thanksgiving had been the final step of a plan already underway.
The email proved it.
Harper had written to him weeks earlier:
“Can you get the rest from Brier’s fund? The motorcycle should cover the gap. She doesn’t need it if she stays here.”
Once I stopped seeing that message as a single request, earlier events changed meaning.
Harper’s supposed emergency loans.
Her credit-card balances.
Her sudden obsession with qualifying for a mortgage.
Doyle’s August withdrawal.
My mother’s repeated insistence that I remain at home because “the family needs you close.”
They had never sat together and announced a conspiracy in some dramatic meeting.
They didn’t need to.
Their assumptions fit together naturally.
Brier would stay.
Brier would pay.
Brier would complain quietly, if at all.
Brier would eventually sign.
That was the real system.
Harper had used my loans to improve her credit profile.
Doyle had taken the emergency savings months before telling me.
Then he sold the Harley after Harper identified it as another source of money.
Finally, they placed the co-sign form beside my Thanksgiving plate after most of the damage was already irreversible.
The timing mattered.
They hadn’t wanted permission.
They wanted surrender.
If they told me before taking the money, I could stop them.
If they told me after taking everything, they believed I would think, What’s the point of fighting now?
Then the mortgage form would become one more sacrifice.
That realization changed my anger.
It made it colder.
I called Quinton.
“Keep going.”
He asked whether Doyle had contacted me about settlement.
“No.”
“Then we follow the process.”
That was enough.
A few days later, Mavis left a voicemail.
She didn’t apologize.
She said, “I wish you could understand why we were trying to help your sister.”
I listened once.
Then deleted it.
Helping Harper had never required taking from me without permission.
Their explanation only worked if my ownership mattered less than her need.
That was the family truth underneath every number.
Harper’s future had been treated as an investment.
Mine had been treated as available capital.
Once I understood that, I stopped waiting for the apology that would make everything emotionally tidy.
There might never be one.
I could still leave.
Chapter 7 — The Empty Garage Hook Became Proof That I Finally Left
Thirty days after Thanksgiving, morning light came through my studio window.
I still hadn’t bought curtains.
My helmet sat on the shelf by the door.
The Harley had disappeared from my life in a single morning, but the helmet remained because Doyle had never owned it.
I opened my nightstand drawer.
The old ignition key lay on the bare wood.
For three years, it had hung from a hook in my parents’ garage.
Every morning before work, I had taken it down.
Every evening, I had returned it.
That routine once felt like home.
Now I understood something different.
I had spent years returning everything to the same place.
My money.
My time.
My loyalty.
My paycheck.
Even when something belonged to me, some part of it always seemed to end up back in that house.
I picked up the key.
For a moment, I could almost hear the motorcycle starting.
Then I set it down again and closed the drawer.
Not discarded.
Not displayed.
Retired.
My phone buzzed.
A message from Sage.
“Overtime Saturday.”
I smiled and typed, “I’ll be there.”
The money would go into my account.
The account had one name.
My lease had one name.
The Civic title had one name.
None of those things were glamorous, but they measured exactly what they claimed to measure.
Three miles away, Doyle and Mavis were learning how expensive their household had always been.
Harper and Nico were living in their apartment instead of the Weller Road house.
Ty had made his own decision about how much contact he wanted with Doyle.
Quinton was handling the financial dispute through the appropriate civil process.
I wasn’t monitoring any of them.
That might have been the biggest change.
For years, I knew when my parents’ mortgage was due. I knew when Harper’s insurance drafted. I knew when the property-tax installment arrived.
I had mistaken knowing everyone’s financial emergencies for being part of a family.
Now I knew when my rent was due.
That was enough.
There was no miraculous reconciliation.
Doyle never became the father I had thought he was just because consequences arrived.
Mavis never found a sentence capable of turning what happened into a misunderstanding.
Harper never returned the years in which she treated my stability as something she could spend.
Maybe one day those relationships would change.
Maybe they wouldn’t.
I no longer built my plans around that possibility.
Before leaving for work one morning, I put on my jacket and glanced at the shelf.
The helmet remained there.
The drawer remained closed.
I took my apartment key instead.
Outside, my old Civic started on the first turn.
I drove toward the plant as the sun came over the warehouses.
Sage was already at her station when I arrived, safety glasses on, coffee beside her machine.
She looked over.
“You’re early.”
“Couldn’t sleep.”
“Thinking about them?”
I considered the question.
Then I shook my head.
“No. Thinking about overtime.”
She laughed softly and turned back toward her machine.
I clocked in.
A steel blank was waiting at my station.
I loaded it into the lathe, entered the program, checked the setup, and watched the machine begin its first pass.
When the finished piece came out, I measured it.
The tolerance was right.
For years, I had thought I was the daughter who happened to live closest.
My parents thought I was the daughter who would never leave.
Harper thought I was the sister whose money would always be available because I had no “real” future requiring it.
We had all misunderstood the same person.
The difference was that I finally corrected the measurement.
And this time, I didn’t put myself back on the hook.
The End
Disclaimer: This story is a work of fiction. Names, characters, businesses, events, and incidents are either products of the author’s imagination or used fictitiously. Any resemblance to actual persons, living or dead, or actual events is purely coincidental! Thank you! 💓