My Sister Mocked My Old Honda And Said I Could Barely Afford Gas, Then Spent Sunday Teaching Me About Money.
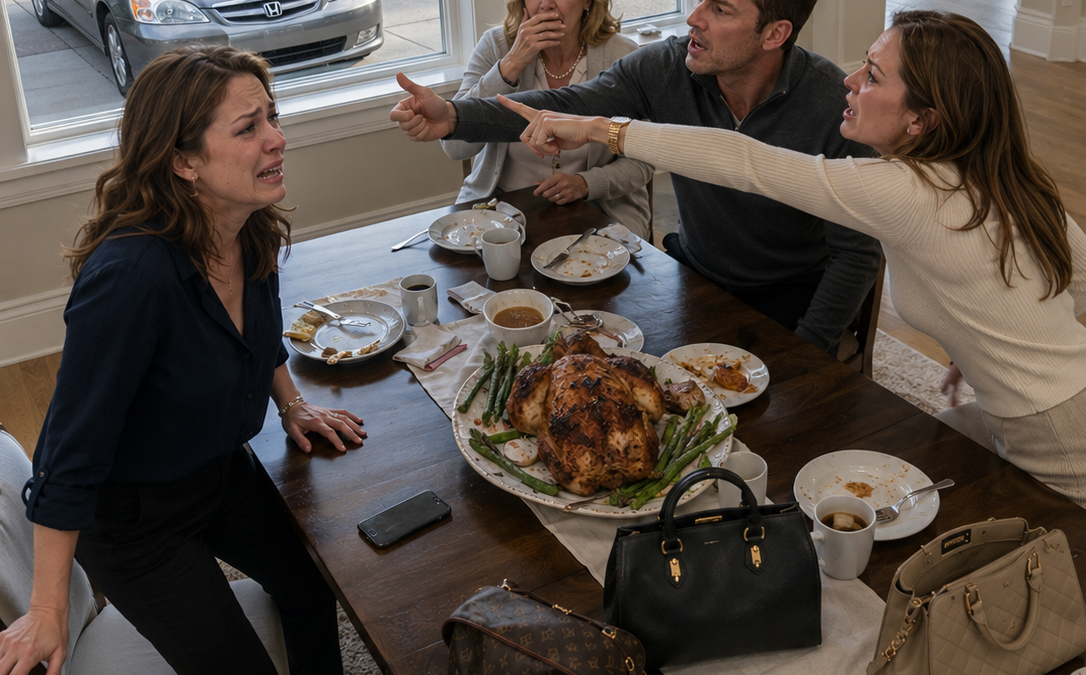
My Sister Mocked My Old Honda And Said I Could Barely Afford Gas, Then Spent Sunday Teaching Me About Money. The Next Morning She Called In Panic About Her Delinquent Mortgage. She Had No Idea The Investment Company Now Holding Her Loan Was The Company I Founded Eight Years Earlier.
Sunday lunch at Mom’s house had become a monthly tradition I secretly dreaded.
Not because of Mom’s cooking. Her roast chicken could make almost any afternoon worthwhile. I dreaded those lunches because somewhere along the way they had turned into a two-hour presentation about everything my older sister Michelle had accomplished, followed by a gentle family discussion of everything they believed I had not.
That November Sunday followed the script perfectly.
I pulled into the driveway at exactly one in my twelve-year-old Honda Civic and parked behind Michelle’s new BMW X5 and Brad’s Tesla Model S. From the street, Mom’s driveway looked like a luxury-car advertisement with my dented Honda accidentally photobombing it.
Michelle saw me through the front window.
“There’s our little penny pincher.”
She said it with a smile when I came inside, just affectionate enough that objecting would make me look humorless.
Mom hugged me.
“Rachel, honey, you look tired. Are you eating enough? I worry about you trying to make ends meet on that tiny salary.”
“I’m fine, Mom.”
I hung my coat beside Brad’s designer jacket and one of Michelle’s expensive handbags.
That was the difference between us, according to my family.
Michelle looked successful.
I did not.
She had the BMW, the clothes, the renovated house and the impressive title of senior marketing director.
Brad talked constantly about real-estate investments.
I drove an old Honda, dressed simply and told people I worked in financial services.
For eight years, my family had interpreted that as struggling.
I had stopped correcting them.
Michelle settled into the living-room armchair and resumed describing a major advertising account worth $2.3 million annually.
“They specifically requested me,” she said. “My track record with luxury brands made the difference.”
Mom beamed.
“That’s wonderful, sweetheart.”
Then she turned toward me.
“What about you, Rachel? How are things at your… what is it you do again?”
“I work in financial services.”
Michelle barely looked up from her phone.
“Still at that little credit union?”
I took a breath.
“That’s sweet,” she continued. “It’s nice you found something stable, even if it doesn’t pay much.”
Technically, I had once worked at a credit union.
For six months.
Eight years earlier.
What nobody at that table knew was what I had done afterward.
But explaining it had become exhausting, and somewhere along the way I became curious about something uncomfortable.
How would my family treat me if they truly believed I had no money?
I already knew the answer.
They loved me.
But with pity attached.
At lunch, Brad discussed a downtown Seattle commercial property he was converting into luxury condominiums.
“The construction loan alone is $4.2 million,” he said proudly. “But we’re looking at eight-figure returns when the units sell.”
Mom practically glowed.
“You two are just so good with money.”
Michelle smiled.
“Brad has an eye for investments.”
I continued cutting my chicken.
The strange part was that there was a reasonable chance money connected to my firm had financed Brad’s project. Commercial real estate was one of our major investment areas.
I said nothing.
Brad finally turned toward me.
“What about you, Rachel? Any big financial plans?”
His eyes moved through the window toward my Honda.
“Maybe saving for a new car?”
“The car runs fine.”
Michelle gave me a sympathetic smile.
“At some point you should upgrade. Image matters if you want to advance professionally.”
“My career is going well.”
“Is it?”
She set down her fork and looked at me with genuine concern.
“Rachel, I’m saying this because I love you. You’re thirty-four. You’re still driving a car from 2011, still living in that little apartment, still shopping at discount stores. At some point you have to invest in yourself.”
Mom added gently, “There’s nothing wrong with being frugal.”
“Frugal is different from being stuck,” Michelle said.
Brad nodded.
“In business, perception matters. If you look like you’re struggling, people assume you’re struggling.”
I looked at both of them.
“You’re probably right.”
That encouraged Michelle.
She offered to introduce me to her friend Stephanie at a downtown wealth-management firm.
“They’re always looking for entry-level advisors.”
“Entry-level?”
“Well, you’d need to start somewhere.”
Brad suggested upgrading my wardrobe before any interview because clients would not trust somebody who “looks like she shops at Target.”
“I do shop at Target sometimes.”
They exchanged a look.
Michelle leaned closer.
“You’re a smart woman. You deserve better than this. But you have to stop being content with mediocrity.”
Mediocrity.
That word stayed with me.
Mom patted my hand and suggested Michelle introduce me to more successful people who could mentor me.
I nodded because arguing would have required explaining a life none of them had bothered to ask about for years.
After lunch, coffee brought another round of concern.
When I mentioned working through part of the holidays, Michelle shook her head.
“You work too much for too little money.”
Brad added, “If you’re putting in those hours, at least make sure you’re compensated.”
Mom suggested a career with greater growth potential.
Then my phone buzzed.
A message from my assistant appeared.
“Chin Industries deal closed successfully. $340 million acquisition finalized. Congratulations.”
I read it once and put my phone away.
Michelle noticed.
“Work texting you on Sunday?”
“It’s fine.”
“No, Rachel. That’s what I mean. They take advantage of you because you don’t value yourself.”
I almost smiled.
Then I asked, “What do you think I’m worth?”
Michelle actually considered it.
“With your age and education? At least sixty thousand. Maybe seventy if you negotiate.”
Brad nodded seriously.
“Seventy-five if you’re really good.”
I nearly swallowed my coffee the wrong way.
Last year, the management fees generated by the company I had founded exceeded $127 million.
“That seems reasonable,” I managed.
Michelle spent the next half hour teaching me about retirement planning.
She and Brad hoped to reach a two-million-dollar net worth by forty.
She explained index funds.
Brad explained asset allocation.
Michelle warned me that understanding compound interest and actually implementing it were different things.
When I told her I had been investing for ten years, she asked how much I had saved.
“It’s hard to say exactly. Markets fluctuate.”
She sighed.
“If you don’t know your net worth, that’s a problem.”
My actual personal net worth was a little over $400 million.
I finished my coffee.
By four, I could not listen anymore.
Michelle followed me to the front door and gently caught my arm.
“I’m serious about helping you. Let me get you an interview with Stephanie. Think about the clothes, the car, the apartment. If you want people to take you seriously, you have to look the part.”
“That’s kind of you.”
I hugged Mom, accepted a container of leftover chicken and walked toward my Honda.
Through the window, I could see Michelle and Brad still talking.
Probably about me.
I drove home and took three investor calls involving Singapore, London and New York.
My “tiny apartment” was actually a 3,200-square-foot penthouse overlooking Elliott Bay, purchased in cash through a holding company five years earlier.
Sunday night, I reviewed reports for several Cascade Capital transactions and went to bed without thinking much more about lunch.
Monday morning, I reached my office on the forty-eighth floor of Columbia Center before six.
At seven, my assistant Jennifer entered carrying contracts and her tablet.
“One more thing,” she said. “Michelle Thompson called the main line.”
I looked up.
“My sister?”
“She said her bank told her to contact us.”
“About what?”
Jennifer checked the screen.
“A mortgage problem.”
Something cold and strange settled in my stomach.
I opened our internal asset system and typed Michelle’s address.
847 Maple Street.
Bellevue.
The file appeared.
Then I saw the lender.
Pacific Northwest Bank.
And beneath it:
Current owner: Cascade Capital Management.
I stopped breathing for a second.
💚 Part 2…
The mortgage had been part of a distressed-loan portfolio we purchased six months earlier.
I opened the payment history.
Original loan: $712,000.
Current balance: approximately $687,000.
Three delinquent payments.
Foreclosure proceedings authorized.
“Get Michelle on the line.”
Two minutes later, her voice exploded through my office phone.
“Rachel, thank God. Something terrible is happening. Our bank sold our mortgage to some investment company called Cascade Capital. They’re threatening foreclosure.”
I stared at her file.
“Michelle, the records show three missed payments.”
“How would you know?”
“You’re behind.”
“We were late a couple times. Brad’s development has cash-flow issues.”
“How late?”
“A month. Maybe two.”
“That is missing payments.”
She exhaled shakily.
“Can’t you help? You work in finance. Maybe you know someone who can negotiate with this Cascade Capital company.”
I looked through the glass wall of my office at forty-eight floors of Seattle beneath me.
Yesterday my sister had explained compound interest to me.
Yesterday she suggested I apply for an entry-level wealth-management job.
Yesterday she told me to stop accepting mediocrity.
Now she wanted me to find somebody powerful enough to save her house.
“Michelle,” I said carefully, “I need to tell you something.”
“What?”
“I am Cascade Capital.”
Silence.
“I’m the founder and CEO of Cascade Capital Management.”
Still nothing.
“We manage $8.3 billion in assets.”
Her breathing changed.
“Including your mortgage.”
𝑻𝒉𝒆 𝒏𝒆𝒙𝒕 𝒑𝒂𝒓𝒕 𝒊𝒔 𝒄𝒐𝒎𝒊𝒏𝒈! 𝑳𝒆𝒂𝒗𝒆 𝒂 “𝑮𝒐𝒐𝒅” 𝒃𝒆𝒍𝒐𝒘 𝒕𝒐 𝒔𝒉𝒐𝒘 𝒚𝒐𝒖’𝒓𝒆 𝒆𝒙𝒄𝒊𝒕𝒆𝒅 𝒇𝒐𝒓 𝒕𝒉𝒆 𝒏𝒆𝒙𝒕 𝒑𝒂𝒓𝒕 𝒂𝒏𝒅 𝒘𝒆’𝒍𝒍 𝒔𝒆𝒏𝒅 𝒊𝒕 𝒓𝒊𝒈𝒉𝒕 𝒂𝒘𝒂𝒚 👇👇)
Michelle’s voice came through my office phone on Monday morning sounding nothing like the confident woman who had spent the previous afternoon teaching me how money worked. “Rachel, thank God. Something terrible is happening. Our bank sold our mortgage to some investment company, and they’re threatening foreclosure.” On one of my monitors sat the file for 847 Maple Street in Bellevue: original loan $712,000, current balance around $687,000, three delinquent payments and foreclosure proceedings authorized. Michelle did not yet know why I could see those numbers, or why Pacific Northwest Bank had directed her to the office where I sat forty-eight floors above downtown Seattle. Less than twenty-four hours earlier, she had looked at my old Honda, my inexpensive clothes and the life she thought I lived and told me I needed to stop being content with mediocrity. Now her house belonged, financially speaking, to a company she had never realized was mine.
Sunday lunch had become the stage where that misunderstanding performed itself every month. I arrived at Mom’s house in my twelve-year-old Honda Civic and parked behind Michelle’s BMW X5 and Brad’s Tesla Model S, making the driveway look like a luxury advertisement with one dented sedan included by mistake. “There’s our little penny pincher,” Michelle called when I entered. Mom hugged me, studied my face and said, “Rachel, honey, you look tired. Are you eating enough? I worry about you trying to make ends meet on that tiny salary.” I answered that I was fine and hung my coat beside Brad’s three-thousand-dollar designer jacket and Michelle’s expensive handbags. They were not cruel people in the theatrical sense. Their condescension came wrapped in concern, which sometimes made it harder to resist.
Michelle was thirty-seven and thriving visibly. She had just been promoted to senior marketing director at an advertising firm where she had worked for six years, and that afternoon she described a $2.3 million annual client account that had specifically requested her. Brad, thirty-nine, talked about commercial real estate as if every project were proof of his financial genius. Mom listened proudly while I sat on the sofa and became the inevitable comparison. “What about you, Rachel?” she asked. “How are things at your… what is it you do again?” I told her I worked in financial services, which was true. Michelle assumed I still worked at the small credit union where I had spent six months eight years earlier. “That’s sweet,” she said. “It’s nice you found something stable, even if it doesn’t pay much.” I did not correct her.
At lunch Brad explained that he had purchased a distressed commercial building downtown and planned to turn it into luxury condominiums. “The construction loan alone is $4.2 million, but we’re looking at eight-figure profits when the units sell.” Mom told them they were wonderful with money. I quietly considered the possibility that a fund connected with my own firm had financed some portion of Brad’s project because Cascade Capital Management, the company I founded after leaving the credit union, managed $8.3 billion in assets and had significant commercial-real-estate exposure across the Pacific Northwest. I had personally approved hundreds of transactions large enough that I no longer recognized every borrower by name.
Brad eventually nodded toward my Honda outside and asked whether I had plans to save for a newer car. When I said the car worked, Michelle explained that image mattered if I wanted to advance. “You’re thirty-four,” she said. “Still driving a 2011 car, still living in that little apartment, still shopping at discount stores. There’s nothing wrong with being frugal, but eventually you have to invest in yourself.” Brad agreed that successful people needed to look successful. I told them my career was going well. Michelle’s expression softened with pity. “Is it, though?” She offered to introduce me to Stephanie, a friend at a downtown wealth-management firm that sometimes hired entry-level advisors. Brad advised me to upgrade my wardrobe because clients would not trust someone who looked like she shopped at Target. I admitted that I did shop there sometimes, and they exchanged a look that told me the confession proved everything.
The conversation worsened after coffee. Michelle told me I worked too much for too little money, Brad said I should demand better compensation, and Mom suggested a career with more growth potential. My phone buzzed with a message from my assistant confirming that a $340 million acquisition involving Chin Industries had closed successfully. I put the phone away, but Michelle noticed the Sunday interruption and told me my employer was taking advantage because I failed to value myself. When I asked what she thought I should be earning, she estimated sixty to seventy thousand dollars, perhaps seventy-five if I negotiated well. I almost choked on my coffee; Cascade Capital’s management fees alone had produced roughly $127 million in revenue the previous year, and my compensation exceeded her estimate by a scale so wide it no longer felt useful to explain.
Chapter 2
Sunday Lunch Turns Into A Humiliating Lecture About My Life
Michelle leaned farther into the role of financial mentor once she realized I was not resisting. She and Brad planned to accumulate a two-million-dollar net worth by forty and eventually increase that number enough to retire early without sacrificing the lifestyle they considered normal. Mom reacted as though they were discussing generational wealth. Michelle explained that five million dollars was probably the minimum for comfortable retirement now, perhaps ten if a person wanted to live well. I nodded politely while knowing my personal net worth sat just above $400 million, not including the full potential value of my equity in Cascade. Money like that is abstract until you spend it, and I had discovered years earlier that visible consumption did very little for me.
Brad asked whether I had started investing for retirement. I said I had investments. Michelle warned me not to leave everything sitting in a savings account and began describing index funds. When I told her I understood them, she adopted the slow voice people use with children and explained that investing involved asset allocation, risk management and compound interest. “I’ve been investing for ten years,” I said. She asked how much I had saved. “It’s hard to say exactly. Markets fluctuate.” That answer made her sigh. “Rachel, if you don’t even know your net worth, that’s a problem.” I knew it down to daily valuations if I wanted to, but admitting that would have transformed the afternoon from mildly insulting to unbelievable.
Mom suggested Michelle help me set up a portfolio. Michelle agreed but warned there probably was not much to work with at my income level, so a target-date fund might be the safest beginning. The condescension finally became exhausting enough that I stood to leave. Michelle followed me to the front door and caught my arm. “I’m serious about helping you. Let me talk to Stephanie. Maybe she can get you an interview.” Then she glanced toward my coat, hair and car. “Think about what we discussed. If you want to be taken seriously, you have to look the part.” I thanked her, hugged Mom and carried a container of leftover roast chicken toward the Honda.
My drive home took twenty minutes, during which I participated in three calls with investors and partners in Singapore, London and New York. My “tiny apartment” was a 3,200-square-foot penthouse in one of downtown Seattle’s most exclusive residential buildings, purchased in cash five years earlier through a holding company because privacy mattered more to me than impressing anyone with a property record. Floor-to-ceiling windows overlooked Elliott Bay, where ferries and container ships moved through the darkening water. I spent the evening reviewing Cascade Capital acquisitions: boutique hotels in California, a struggling Austin technology company and a renewable-energy infrastructure opportunity across the Pacific Northwest. Sunday was often the only quiet time before global markets and investor demands accelerated again.
I had not hidden my success initially. Eight years earlier, after six months at the credit union learning lending operations and building relationships, I founded Cascade Capital and started raising money for small private investments. I tried describing the work to my family several times, but nobody understood why I would leave a stable employer to build a fund they had never heard of. As Cascade expanded, their questions became less specific rather than more. Michelle continued believing I worked at the credit union because she never asked where my office was, who employed me or why I traveled so often. At some point, correcting the assumption began to feel like begging for interest.
There was another reason I remained vague. I wanted to know whether my family’s affection depended on visible success. Michelle loved me, but she loved me with lectures attached. Mom loved me with constant worry. Brad tolerated me with the generous confidence of a man who believed he had already won the race. None of them abandoned me because they thought I struggled, which mattered. Yet their love came packaged with the assumption that my judgment, career and finances were inferior. I sometimes wondered how they would behave if they discovered the cheap clothes, old car and modest public profile were choices rather than limitations.
Monday morning, I reached Cascade’s office on the forty-eighth floor of Columbia Center before six. Jennifer arrived with contracts, investor reports and a list of calls. “Michelle Thompson called the main line,” she said. “She says she’s your sister and the bank gave her our number about a mortgage issue.” I frowned, pulled up our asset system and entered her address. The result stopped me cold. Cascade had purchased a distressed mortgage portfolio from Pacific Northwest Bank six months earlier, and among approximately three hundred loans sat Michelle and Bradley Thompson’s Bellevue home.
The detailed file showed a pattern their Sunday conversation had concealed. The house had been purchased three years earlier for $890,000 with a $712,000 mortgage. The current loan balance was approximately $687,000. Payments were seriously delinquent, fees were accumulating and foreclosure proceedings had already been authorized under the servicing terms. I stared at the address, remembering Michelle explaining financial discipline while her BMW sat outside Mom’s house. Then I told Jennifer, “Get my sister on the line.”
Chapter 3
One Mortgage File Reveals My Sister Is Financially Falling Apart
Michelle answered before the second ring finished. “Rachel, for Pete’s sake, I’ve been trying to reach you all morning. Our bank says they sold our mortgage to Cascade Capital and now someone is threatening foreclosure.” Her voice was thin with panic. I asked exactly what Pacific Northwest had told her, then listened as she insisted they had never missed a payment. On my screen were three missed payments during the preceding four months, plus penalties and fees. “Michelle, the account history shows three delinquencies since July.” Silence followed. “How would you know that?”
She tried to reframe the situation. They had been “a little late” because Brad’s development project suffered cash-flow problems, but they always intended to catch up. I asked what little late meant. “A month, maybe two sometimes.” I told her a mortgage payment more than thirty days late was delinquent whether she eventually intended to pay it or not. When I asked when they last made a complete payment, she hesitated because Brad supposedly managed those details. It was November; the file suggested no current payment since late summer. Their financial image was collapsing line by line on my screen.
Then Michelle asked for help. “You work in finance. You must know somebody who can negotiate with this Cascade Capital company.” I turned my chair toward the window and looked down at Seattle. The irony was almost too sharp. Yesterday she offered me an interview with an entry-level wealth manager, explained compound interest and advised me to buy better clothes. Now she wanted access to somebody important enough to influence the company holding her house. “Michelle, I need to tell you something.” Her voice became impatient. “What?” I said, “I am Cascade Capital.”
She laughed once because disbelief sometimes comes out that way. “That’s not funny.” I told her it was not meant as a joke. “I’m the CEO and founder of Cascade Capital Management. I founded it eight years ago. We manage $8.3 billion in assets, including your mortgage.” The call went completely silent. I could hear faint typing. Then she inhaled sharply. “Oh my God.” More typing followed. “Rachel, is this real? This says you’re worth four hundred million dollars.” I told her the number moved with market conditions, but it was approximately accurate.
“This can’t be real,” she whispered. “You work at a credit union.” I explained that I had worked there for six months in 2016 while learning the business and preparing to launch Cascade. I had not been an employee anywhere else since. She accused me of letting everyone think I could barely afford gasoline. “No,” I corrected her. “You thought that. I never told you I couldn’t afford gas. I said my Honda ran fine.” She asked why anybody with my resources would drive an old car, shop at Target or avoid an expensive public lifestyle. I asked why wealth had to be visible before she considered it real.
Her voice became smaller. “You own our mortgage.” I clarified that Cascade owned it as part of a roughly three-hundred-loan portfolio, not because I had targeted her. I personally approved large acquisitions but had never connected her street address to the portfolio until that morning. Then I gave her the amount currently due: approximately $18,347 including delinquent payments, penalties and related charges. Michelle began crying. “We don’t have eighteen thousand dollars.” I thought of the Italian vacation they had taken, the planned kitchen renovation, the BMW, the Tesla and Brad’s repeated claims that his development would generate eight-figure profits.
She asked whether I could simply forgive the debt because we were sisters. I told her Cascade was a real investment company with investors, legal duties and contractual obligations. I could not erase valid mortgage debt for relatives because doing so would misuse assets entrusted to the firm. “But we’re family.” Her words landed differently after Sunday. “Yesterday, when we were family, you told me I needed financial discipline, better investments and a stronger career. You told me to ask for what I was worth and stop settling for mediocrity.” Michelle answered that this was different. “Is it?” I asked.
I looked at her budget information and saw what the visible luxury had been hiding: payments stretched across vehicles, travel, renovations and development commitments while the most basic obligation—the house—was repeatedly pushed aside. The house itself had appreciated to around $940,000, which meant foreclosure would not necessarily leave them penniless, but it could force them out of the lifestyle they had organized their identity around. “You’re not facing this because you don’t earn money,” I said. “You’re facing it because you keep spending as if appearances are more important than cash flow.” For the first time in years, Michelle had no advice ready for me.
Chapter 4
She Calls For Help And Learns Who Owns Everything Now
I told Michelle the company could discuss a loan modification if she and Brad demonstrated a realistic ability to make future payments. Her relief lasted only until I explained what realistic meant. They would need a complete financial picture, proof of income, debts, expenses and a budget showing the mortgage could be sustained. Luxury spending that interfered with housing payments would matter. “So what are we supposed to do?” she demanded. I answered plainly: sell the BMW, reconsider the Tesla, cancel Aspen and stop budgeting around the image they wanted other people to see.
“We can’t sell our cars,” she said. “Brad needs the Tesla for his image. Clients expect a successful developer to look successful.” I leaned back in my chair and remembered sitting at Mom’s table while Brad explained exactly the same philosophy to me. “Brad’s image is part of what got you here.” Michelle protested that his real-estate career depended on perception. I told her banks did not accept perception as mortgage payments. If the choice was between appearing wealthy and keeping the house, then the financially responsible decision should be obvious to somebody who spent yesterday lecturing me about responsibility.
“What will people think?” she asked quietly. The question revealed the real terror underneath everything else. Michelle was afraid of losing the house, but she was also afraid the BMW disappearing from the driveway would tell friends that the success story was not as solid as it looked. “People might think you’re making responsible choices,” I said. “Or they may not think about you nearly as much as you imagine.” She began crying again and asked how I had become so successful while she and Brad were slipping toward foreclosure. For once, there was no accusation in her voice. It sounded like a genuine question.
“I built something instead of spending money to look like I had built something,” I said. Michelle told me she did not understand the difference. I explained wealth signaling versus wealth creation. Buying the right car, clothing or vacation could make strangers assume you were prosperous, but those purchases consumed resources. Actual wealth grew from owning productive assets, businesses and investments capable of generating more value over time. Cascade had been created quietly while I drove an old Civic, reinvested profits, kept my personal spending relatively modest and concentrated on building an institution rather than an image.
She reminded me that she had said image mattered in business. “You said that,” I corrected. “I said my career was going well.” Her assumptions had filled the rest. Nobody ever asked whether I owned my company, what kind of assets I managed or how much capital passed through my office. They saw an old Honda and decided the evidence was complete. Michelle had done the same thing with her own life in reverse: she saw expensive cars and a renovated kitchen and decided those objects proved financial security, even while the mortgage file told another story.
Jennifer appeared at my door holding a note: BOARD MEETING IN 10 MINUTES. I told Michelle I needed to go and that our loan-modification team would contact her that afternoon. They would evaluate the situation professionally, without special punishment and without special forgiveness. Michelle asked me to wait. “Why didn’t you tell us?” she said. “Why let us think you were struggling?”
I turned toward Elliott Bay before answering. Ferries crossed the water beneath clouds, and beyond them container ships moved billions of dollars in trade through the port, some connected to financing structures my firm touched indirectly. “Because I wanted to see whether you would love me when you thought I was unsuccessful.” Michelle immediately said they did love me. “I know,” I answered. “But yesterday you loved me while pitying me. Today you know I’m successful. I don’t know yet what that changes.”
She went quiet. I told her the hardest part was not the financial advice itself; some of it was perfectly reasonable. It was the certainty with which she assumed I needed saving because my life did not display the symbols she respected. “You never asked me what I had built,” I said. “You decided what I was worth from my car.” The line disconnected a few minutes later, and I sat alone before walking into the boardroom, where people who trusted me with billions of dollars were waiting for my opinion on risk.
Chapter 5
Her Luxury Image Cracks When The Numbers Finally Speak Clearly
The board meeting continued like any other Monday. We reviewed quarterly performance, debated new opportunities and examined areas where risk had increased. Cascade was having an excellent year, outperforming several targets and expanding into investments that would position us well for future growth. Nobody in the room knew that, minutes before I arrived, my sister had asked me to save the house whose mortgage sat inside one of our distressed portfolios. That separation mattered. I had built a company with fiduciary responsibilities, not a personal bank account from which I could rewrite contracts whenever family became uncomfortable.
Our loan-modification team contacted Michelle and Brad later that day. I stayed out of the negotiation beyond making sure they received the same fair process available to similarly situated borrowers. They would need to show what they earned, what they owed and what they were willing to change. Whether they kept the house would depend largely on their willingness to align their actual spending with their actual resources. I did not need to punish them. Their numbers were already doing something more effective than anger could.
For the rest of the afternoon I kept remembering the driveway at Mom’s house: BMW, Tesla, Honda. Everyone had treated those three cars like financial statements. Michelle’s BMW meant achievement. Brad’s Tesla meant confidence. My old Honda meant failure. Yet the Honda had no meaningful effect on my life because I could replace it whenever I wanted, while their luxury vehicles were part of a spending structure competing with their mortgage for cash. Objects had told exactly the wrong story because everyone looking at them wanted the story to be simple.
I also had to admit that my secrecy was not entirely neutral. In the early years, keeping Cascade private protected me from family interference and allowed me to build without endless commentary. Later, invisibility became a kind of experiment. I wanted to know whether they loved me without wealth, and they did, but not without judgment. Mom’s concern was real. Michelle’s offers to help were, in her own way, sincere. Brad probably believed his advice. The problem was that affection does not become respectful merely because intentions are good. They had spent years speaking down to me because I did not perform success in a language they recognized.
That did not mean I needed to arrive at the next lunch in a supercar. The temptation crossed my mind, admittedly. I could imagine pulling behind Michelle’s BMW in something absurdly expensive and watching the entire family reconstruct my identity before dessert. But that would still make their metric my metric. If I bought a nicer car, it should be because I enjoyed driving it, not because I needed a vehicle to prove a point my balance sheet already made irrelevant.
Maybe I would upgrade the Honda eventually. Twelve years was a long time, and the dent in the passenger door had started to annoy me. Maybe I would also stop working so hard to conceal the penthouse, the company and the parts of my life I had once protected from skeptical family questions. Privacy was healthy; deliberate invisibility could become its own kind of performance. There was a difference between not needing to signal wealth and pretending success had to remain secret to stay pure.
What I would not change was the distinction Michelle finally had to face. Wealth signaling was not wealth creation. Looking successful was not the same as being financially secure. Giving advice was not proof that you were following it. And driving an old Honda did not mean the person behind the wheel needed an entry-level job.
The strangest part was that I did not feel triumphant about owning Michelle’s mortgage. I felt sad that the revelation required a crisis. If she had asked me years earlier, “Rachel, what are you actually building?” I probably would have told her. If Mom had asked to visit my office, I would have shown her. If Brad had ever discussed finance with me instead of at me, we might have discovered we operated in overlapping markets. But people rarely investigate a conclusion they enjoy believing.
Michelle would probably always be my older sister, certain she knew what everyone needed. Mom would probably continue worrying over whether I ate enough no matter how many billions my company managed. Brad might never entirely surrender the belief that clients judged him by his car. Family dynamics do not vanish because one Google search changes the balance sheet.
But something had changed for me.
The next time Michelle advised me to value myself, I would not quietly absorb the insult hidden inside the concern.
The next time somebody mistook simplicity for failure, I could decide whether correcting them was worth the energy.
And if my sister ever tried explaining mortgage discipline to me again, I could politely suggest she speak with her loan-modification specialist.
Sunday afternoon, she had told me nobody else would advocate for what I was worth.
In one sense, she had been right.
I had spent years allowing my family to underestimate me because defending myself seemed unnecessary.
Monday morning reminded me that silence can protect peace, but it can also preserve other people’s assumptions indefinitely.
Outside my office windows, Seattle moved beneath a gray November sky. Thousands of people were going to work, borrowing, investing, spending and making choices that would eventually become numbers on somebody’s screen.
Michelle’s numbers had finally spoken.
So had mine.
The difference was that mine never needed a luxury car to say anything at all.
THE END
Disclaimer: This story is a work of fiction. Names, characters, businesses, events, and incidents are either products of the author’s imagination or used fictitiously. Any resemblance to actual persons, living or dead, or actual events is purely coincidental! Thank you! 💓