“Don’t touch. These were baked for our own grandchildren, not for strangers,
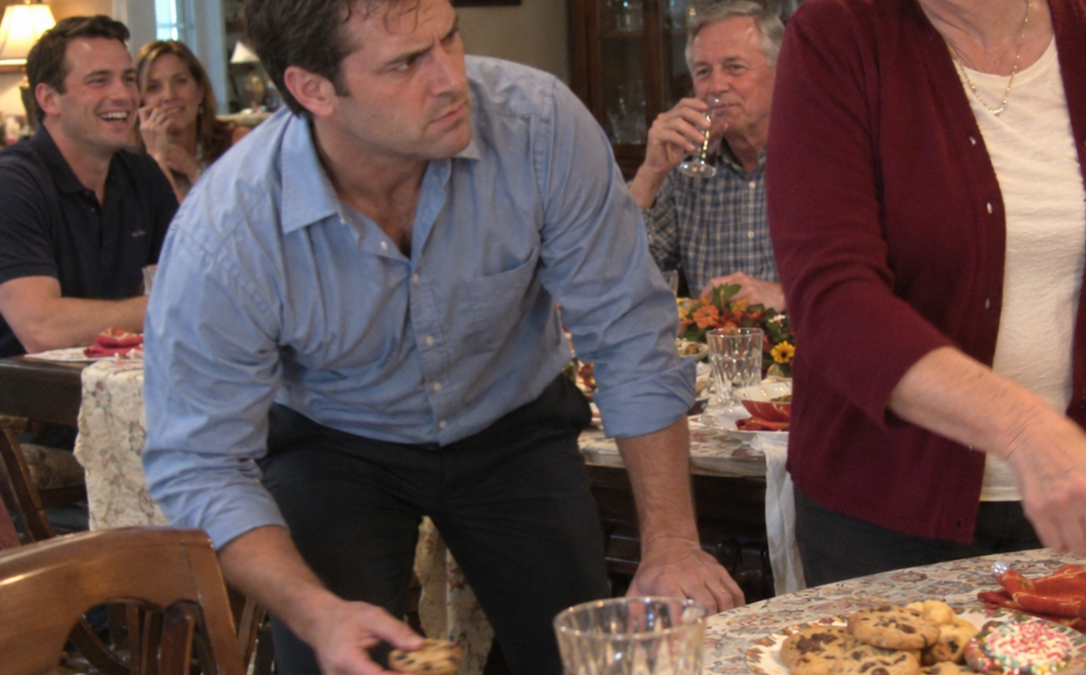
“Don’t touch. These were baked for our own grandchildren, not for strangers,” my mother snapped at my 8-year-old son before slapping his hand away from the cookies. My brother laughed, and my father smiled. I picked up the fallen cookie and took my boy home. An hour later, Dad texted about his loan payment. After six years and more than $60,000, I finally checked where my money had been going…
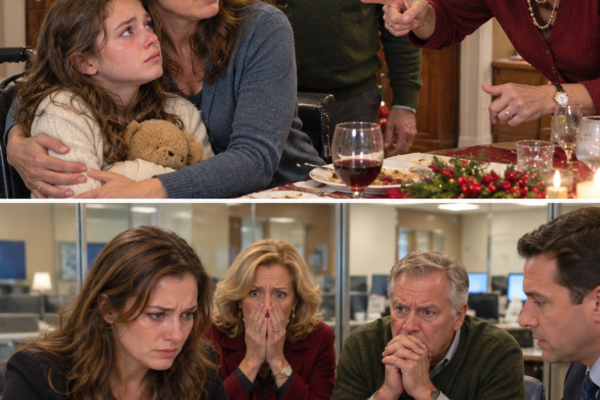
My mother slapped my 8-year-old son’s hand away from a plate of cookies at our family dinner.
“Don’t touch. These were baked for our own grandchildren, not for strangers.”
The cookie fell beneath the dining table.
For a moment, my son, Ethan, just stared at her. Then he looked at me with the kind of confusion no father ever wants to see on his child’s face.
My younger brother, Derek, laughed. My sister joined him. Even my father smiled into his drinking glass.
Nobody told my mother to stop.
I bent down, picked up the cookie, and placed it on the table.
“Come on, buddy. Let’s get your jacket.”
My mother rolled her eyes.
“Oh, Grant, don’t be so sensitive.”
I didn’t answer. I helped Ethan into his coat and took him home.
What my family didn’t know was that, before the following day was over, I would begin questioning a financial arrangement that had quietly taken more than $60,000 from my bank account.
And it started with a text message.
My name is Grant Miller. I’m a divorced father raising my son, and until that dinner, I had spent most of my adult life believing that helping my parents was simply something a good son did.
Dad owned a hardware store. Six years earlier, he’d told me the business was struggling and the bank was threatening foreclosure.
He asked whether I could help with his business loan until things improved.
I agreed.
At first, it seemed temporary. Then the payments became monthly. Sometimes there were additional requests when Dad said an unexpected bill had come due.
I had Ethan to provide for, but I kept finding room in my budget.
My parents had helped me when I was younger. I believed I was returning that kindness.
Dad always made it sound as though the store depended on those payments.
Meanwhile, Derek seemed to have a different arrangement with our parents.
Dad often complained that my younger brother couldn’t manage money. He described Derek as irresponsible and insisted he had nothing to do with the business.
I never questioned it.
I was busy working, raising Ethan, and trying to keep everyone happy.
But my mother’s treatment of Ethan had been getting harder to excuse.
She made little distinctions between him and the other grandchildren. Sometimes it was a comment about manners. Other times, it was the way she seemed to welcome everyone else while expecting Ethan to remain quiet and grateful.
I kept telling myself that she was old-fashioned and didn’t always understand how her words sounded.
That evening, she made herself perfectly clear.
When we got home, I ordered pizza.
Ethan sat beside me, picking at a slice. He was usually full of questions after visiting his grandparents, but that night he barely spoke.
I wanted to ask what he was thinking. Instead, I let him eat.
About an hour after we left my parents’ house, my phone buzzed.
It was Dad.
“Don’t forget tomorrow’s payment on my loan.”
I read the message twice.
Not one person had called to ask whether Ethan was okay.
My father hadn’t mentioned what his wife had done or why we’d left early.
But he remembered the money.
I opened our message history.
There were months of reminders, requests for additional help, and explanations about why another payment was necessary.
I kept scrolling.
Then I opened my banking app.
I had never totaled everything I’d sent over the years. I knew it was substantial, but every payment had seemed manageable when considered separately.
The next morning, Dad called at 7:15.
“Grant, the payment needs to clear by noon. I don’t want another late fee.”
I was making breakfast for Ethan.
“I’ll handle it,” I said.
After Ethan left for school, I sat at the kitchen table and downloaded my payment records.
The total was more than $60,000.
I went through the statements again, checking dates and amounts.
Some transfers matched what Dad had requested. Others went to an unfamiliar account.
The description beside several of them was the same.
Family assistance.
I searched my old emails until I found the original loan agreement Dad had sent me years earlier.
My name wasn’t on it.
I looked through the pages more carefully.
Near the bottom, I found something I hadn’t noticed before.
Derek’s name.
My brother, whom Dad claimed knew nothing about the loan, was listed as a guarantor.
I called him.
“Hey, do you know anything about Dad’s loan?”
He paused.
“Why are you asking?”
“Just checking some records.”
His voice dropped.
“Grant, don’t start digging into that. Dad said everything was settled.”
Then he hung up.
I stared at my phone.
Why would Derek warn me against checking a loan he supposedly knew nothing about?
I called my bank and asked about the unfamiliar transfers. The representative confirmed that I’d authorized them but couldn’t identify the receiving account’s owner.
I requested a review and asked how to stop future payments.
Then I contacted the bank named in Dad’s original loan documents.
They couldn’t release another customer’s private information.
But they confirmed one important detail.
The payments I’d been making weren’t going toward the loan number my father had given me.
For six years, Dad had told me I was helping save his business.
Now I had proof that at least part of his explanation didn’t match the banking records.
I looked at the account numbers again.
My mother’s words from dinner came back to me.
“Not for strangers.”
Apparently, my son was a stranger when he wanted a cookie.
But I had never been a stranger when my father wanted money.
I made an appointment with an attorney and gathered every statement, email, and receipt I could find.
For the first time in six years, I wanted to know exactly what my family had been asking me to pay for.
And one question bothered me more than anything else.
If my money wasn’t going where Dad said it was going, who had actually been receiving it?
CHAPTER 2
I arrived at my attorney’s office carrying six years of financial records.
Some were printed bank statements. Others were emails I’d saved without thinking much about them at the time.
There were messages from Dad asking me to make payments early, requests for additional money, and the old loan agreement he’d sent when the hardware store was supposedly in trouble.
My attorney reviewed the paperwork carefully.
She didn’t immediately tell me I’d been cheated. She asked how the arrangement had started, whether I’d signed anything, and whether my father had ever explained the account numbers.
Then she pointed at a transfer.
“Grant, did your father ever explain why you were paying an account that wasn’t listed in this agreement?”
“No.”
She turned to another statement.
“And these payments marked family assistance?”
“He told me they were related to the business.”
She studied the dates.
Some of the transfers had been made within days of other payments connected to the account my father claimed was overdue.
The pattern raised questions, but she explained that we needed more information before reaching conclusions.
She advised me to stop making voluntary transfers, preserve my correspondence, and avoid accusing anyone until we understood the documents.
I appreciated that.
A part of me wanted to believe there was a reasonable explanation.
For years, I’d thought of my father as a hardworking man who had built a small business and needed help keeping it alive.
I knew how much that store meant to him.
There had been plenty of mornings when he opened early and evenings when he stayed late.
When he’d first asked for help, I hadn’t pictured myself financing anyone’s lifestyle. I’d pictured my father losing something he’d spent years building.
That was why I’d agreed.
And once the payments became routine, I stopped asking questions.
It was easier to send the money than listen to another worried conversation about the store.
But looking at those statements in my attorney’s office, I began to understand how much trust I’d given away without noticing.
That evening, I called Dad.
I told him I was reviewing my records and needed to understand the transfers to the unfamiliar account.
He sounded annoyed immediately.
“Why are you going through all that?”
“Because I need to know where the money went.”
“The business needed help.”
“Then why don’t the account numbers match?”
He avoided answering at first.
Finally, he said, “Your brother needed help. We used some of the money for him.”
I sat down.
“Derek?”
“He has a family, Grant.”
I waited for him to explain why that meant I should have been paying his expenses.
Dad continued talking about family obligations and how everyone needed help sometimes.
“And the loan?” I asked.
“Don’t make this difficult, Grant.”
I ended the call.
I didn’t know the full amount that had gone to Derek. I didn’t know who controlled the other account or why Dad had never told me what he was doing.
But I knew something important now.
My father had accepted payments from me under one explanation while using at least some of that money for a different purpose.
He had never asked whether I agreed.
I thought about the times I’d postponed purchases because Dad needed another transfer.
I thought about Ethan and the careful budgeting that came with raising a child on my own.
And I thought about my brother laughing when our mother slapped my son’s hand.
The next morning, I canceled the automatic transfer.
I also changed my banking passwords and removed the saved payment information.
I left the money already transferred untouched. My attorney had explained that determining whether any of it could be recovered would require proper documentation.
For now, I simply stopped sending more.
Dad called before lunch.
“Grant, what happened to the payment?”
“I canceled it.”
“You can’t just stop paying. The bank expects that money.”
“Then you should call the bank.”
There was a pause.
Dad wasn’t accustomed to hearing that from me.
Normally, when he asked for money, I’d explain what I had available or promise to find a way to help.
If I couldn’t send the full amount immediately, I felt guilty.
This time, I had no apology to offer.
Then he asked, “You’re punishing your whole family over a cookie?”
I looked at the stack of statements on my kitchen table.
“No, Dad. I’m reviewing my finances.”
He hung up.
By dinner, Mom had sent three messages.
The first accused me of being selfish.
The second said Ethan needed to learn respect.
The third insisted that family problems should stay private.
I saved all three.
CHAPTER 3
That evening, as I was helping Ethan get ready for bed, he asked me a question.
“Dad, does Grandma hate me?”
I sat beside him.
“No, buddy. What happened wasn’t your fault.”
He looked down.
“Did I do something bad?”
“No. You didn’t deserve to be treated that way. Adults are responsible for how they treat people.”
He nodded.
I didn’t promise that Grandma would apologize, because I had no reason to believe she would.
I didn’t tell him he had to forgive her, either.
He never asked when we were going back.
That bothered me more than anything my mother had written.
Ethan had once enjoyed visiting his grandparents. Now he was trying to understand why someone who called herself his grandmother could treat him like he didn’t belong.
I couldn’t fix that with a reassuring sentence.
But I could stop taking him somewhere he wasn’t welcome.
The following afternoon, my attorney contacted me.
She had received documents in response to a formal request for records I was entitled to obtain.
One of them was a financial summary prepared for the lender involved with Dad’s business.
My attorney asked me to pay particular attention to the second page.
There, among the figures and descriptions, were my monthly transfers.
They weren’t listed as required loan payments.
They were described as voluntary family contributions.
I read that phrase several times.
“Does that mean the bank wasn’t expecting my payments?” I asked.
“According to this document, your father wasn’t relying on an obligation from you to satisfy the loan,” she explained. “But we should distinguish what these records establish from what still needs to be investigated.”
I looked down at the page.
Six years.
More than $60,000.
All those reminders about deadlines and late fees.
Dad had made the arrangement sound like something I was responsible for maintaining.
Now the paperwork told a different story.
The financial summary also showed expenses associated with Derek’s new house.
Other transfers had gone into an account controlled by my mother.
I knew Derek had been establishing himself financially. What I hadn’t known was that my father was using money I’d sent for the hardware store to help him.
My attorney continued reviewing the records while I tried to understand what I was seeing.
“Does this prove fraud?” I asked.
“Not by itself,” she replied. “But it gives us questions worth asking.”
She recommended a written notice stating that I would make no further payments without a valid explanation and requested a full accounting of how the money had been used.
I followed her advice.
That night, Derek called.
He didn’t ask how Ethan was doing.
He didn’t mention dinner.
His first words were, “You’re making Dad look bad.”
“I’m asking where my money went.”
“He was helping me get established.”
“With my money?”
Derek didn’t answer immediately.
Then he said, “Mom told us you knew.”
I leaned back in my chair.
“Knew what?”
“That Dad was helping everyone. She said you agreed.”
I stared at the papers spread across my table.
“Derek, nobody ever asked me to help pay for your house.”
He became defensive.
He said he’d believed Mom, and I had no way of knowing exactly what she’d told him over the years.
But one thing was clear.
My parents had described the same payments differently depending on which son they were talking to.
To me, they were essential payments for Dad’s struggling business.
To Derek, they were money I had willingly contributed to help the family.
And on the lender’s financial report, they were voluntary contributions rather than required loan payments.
Those explanations were not the same.
I told Derek I wanted to discuss everything with the paperwork present.
He agreed, although he insisted Dad should decide where we met.
Dad chose the hardware store after closing.
I had spent years thinking of that place as the reason for my financial sacrifices.
CHAPTER 4
Now I was walking into it with an attorney.
My father was already there when we arrived.
He looked irritated when he noticed the documents my attorney was carrying.
Derek arrived about ten minutes late.
Mom came in after him.
Dad glanced at my attorney.
“This is a family matter. We don’t need lawyers involved.”
“My money is involved,” I answered.
He looked at me for a moment, then pulled out a chair.
My attorney placed copies of the financial statements and loan records on the table.
She asked him to explain why he’d described my transfers as loan payments when the available records identified them differently.
At first, he claimed there had been confusion.
Then he suggested the bank had made the documents unnecessarily complicated.
My attorney asked him about the transfers associated with Derek’s house.
Dad looked toward my brother.
After more questions, he admitted that some of the money had been used to help Derek and my mother.
Derek stared at him.
“You told me Grant approved everything.”
Mom folded her arms.
“He never said no.”
I looked at her.
Those four words explained a great deal.
I hadn’t said no because I hadn’t been told the truth.
I’d agreed to help Dad with a business loan.
I hadn’t agreed to finance my brother’s housing expenses or send money into an account controlled by my mother.
There was a difference.
And my mother seemed to think my failure to discover the arrangement sooner was the same as giving permission.
I wondered how long she had counted on that reasoning.
My attorney didn’t argue with her.
Instead, she returned to the records.
She asked what amount had actually gone toward the business and what had been used for other purposes.
Dad couldn’t provide a complete answer.
My mother grew increasingly irritated with the questions.
Derek seemed uncomfortable, but he stopped defending the arrangement after hearing Dad admit he’d been told a different version.
I placed one final document on the table.
It was an accounting prepared from my own bank records, showing each transfer, its date, and the total amount.
I pushed it toward Dad.
“I want a full explanation and a repayment proposal. My attorney will handle further communication.”
Dad pushed the papers away.
“You’ll regret turning against your own parents.”
CHAPTER 5
For a moment, I thought about all the times I’d worried about disappointing him.
How often had I agreed to send money because I didn’t want him to think I was ungrateful?
How many times had I rearranged my budget rather than ask him an uncomfortable question?
And after all that, my son couldn’t even reach for a cookie at his grandparents’ dinner table without being called a stranger.
I stood up.
“No, Dad. I regret waiting this long to ask questions.”
Then I left with my attorney.
There was no shouting match.
I didn’t threaten him or demand that Derek choose sides.
The numbers were already on the table.
Now Dad had to explain them.
Two days later, my attorney received an email from my father’s lawyer.
The message acknowledged something important.
My payments had not been required by the bank.
Seeing that admission in writing mattered to me.
Until then, Dad had relied on my willingness to accept his explanations. Whenever I became concerned about money, he reminded me that the store needed help.
Now another attorney was acknowledging that the obligation I’d been led to believe I had never existed in the way Dad had described it.
But the email contained another surprise.
Dad wanted to negotiate before I reviewed the attached records.
My attorney opened the attachment.
It was a proposed repayment agreement.
Dad offered to return part of the money.
There was a condition.
I would have to sign a confidentiality clause agreeing never to discuss the transfers with Derek.
I read it twice.
After years of being told that helping family meant sharing the burden, I was now being asked to protect information from my own brother.
The same brother who’d apparently been told I had agreed to help him.
I asked my attorney what she thought.
She advised me not to sign.
We sent a counterproposal.
I requested a complete accounting and a reasonable repayment schedule without the confidentiality requirement.
I wasn’t interested in embarrassing my parents publicly.
But I wouldn’t agree to silence as the price of recovering money I’d been misled into sending.
Weeks passed.
Dad eventually agreed to terms that my attorney reviewed.
The repayment agreement covered the amount we could document, with monthly payments arranged over time.
The agreement was written and enforceable.
FINAL
It didn’t put all the money back into my account immediately.
And it didn’t erase the years when I’d paid without knowing how my money was being used.
But I finally had something I’d lacked throughout the arrangement.
Clear terms.
A written record.
And the right to ask questions without accepting Dad’s explanations simply because he was my father.
I didn’t pursue a public fight.
I stopped financing an arrangement that had depended on my trust while withholding information from me.
The changes in my relationship with my family were harder to resolve.
Mom never gave me the apology I wanted for Ethan.
She continued treating the dinner incident as an overreaction on my part.
As though the important question was why I’d been upset rather than why she’d slapped a child’s hand and called him a stranger.
Derek and I didn’t suddenly become close.
I understood that he’d been told I knew about the assistance, but I couldn’t forget how easily he’d laughed while Ethan was being humiliated.
I didn’t need to invent excuses for him anymore.
My relationship with Dad became largely about the repayment arrangement.
He made his payments.
I didn’t know whether he regretted misleading me or simply regretted that I’d discovered the truth.
I had stopped trying to determine his private feelings from the things he said when he wanted something.
Then Thanksgiving approached.
Mom called and asked whether I planned to bring Ethan.
Her voice sounded almost ordinary, as though we were discussing the menu for another family dinner.
“Will he be treated like your grandchild?” I asked.
She didn’t give me a direct answer.
Instead, she said, “Your father says you’re making us pay for one mistake.”
I looked toward the kitchen, where Ethan had been helping me decide what we should do for the holiday.
“One mistake doesn’t explain six years of payments,” I replied.
Mom started to object.
I ended the conversation politely.
I didn’t argue about the cookies again.
There was nothing left to explain.
My mother understood what she’d done. My father understood what the financial records showed.
Neither needed another speech from me.
That Thanksgiving, Ethan and I went to spend the day with friends.
Nobody asked why he wanted a cookie.
Nobody told him the food was meant for someone else’s children.
He sat at the table with the rest of us, ate more cookies than he probably should have, and laughed in a way I hadn’t heard during our last visit with my parents.
At one point, he looked over at me.
“Dad, can we come here again next year?”
“Yes, buddy,” I told him.
And I meant it.
For years, I’d treated family loyalty as a bill that kept coming due.
I thought being a good son meant paying when my parents asked, trusting their explanations, and swallowing disagreements because family relationships were too important to damage.
But my parents had been willing to accept my money while allowing my own child to feel unwanted.
I couldn’t make them become different people.
I couldn’t force my mother to apologize or my father to understand what six years of dishonesty had cost us.
What I could do was decide how Ethan and I would live from then on.
My father still makes payments under our agreement.
I still keep the records.
But I don’t automatically send money when somebody invokes the word family.
And whenever I think about that dinner, I remember something smaller than the financial statements and more important than the repayment schedule.
A cookie falling beneath a table.
A little boy wondering what he’d done wrong.
And the moment I finally understood that protecting my son mattered more than keeping my parents comfortable.
I never made another payment on Dad’s loan.
THE END.
I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please leave a comment, like, and share the post. Thank you for reading! ❤️