My husband texted me at 8:17 Tuesday morning, “You’re cut off. Don’t contact me again,”
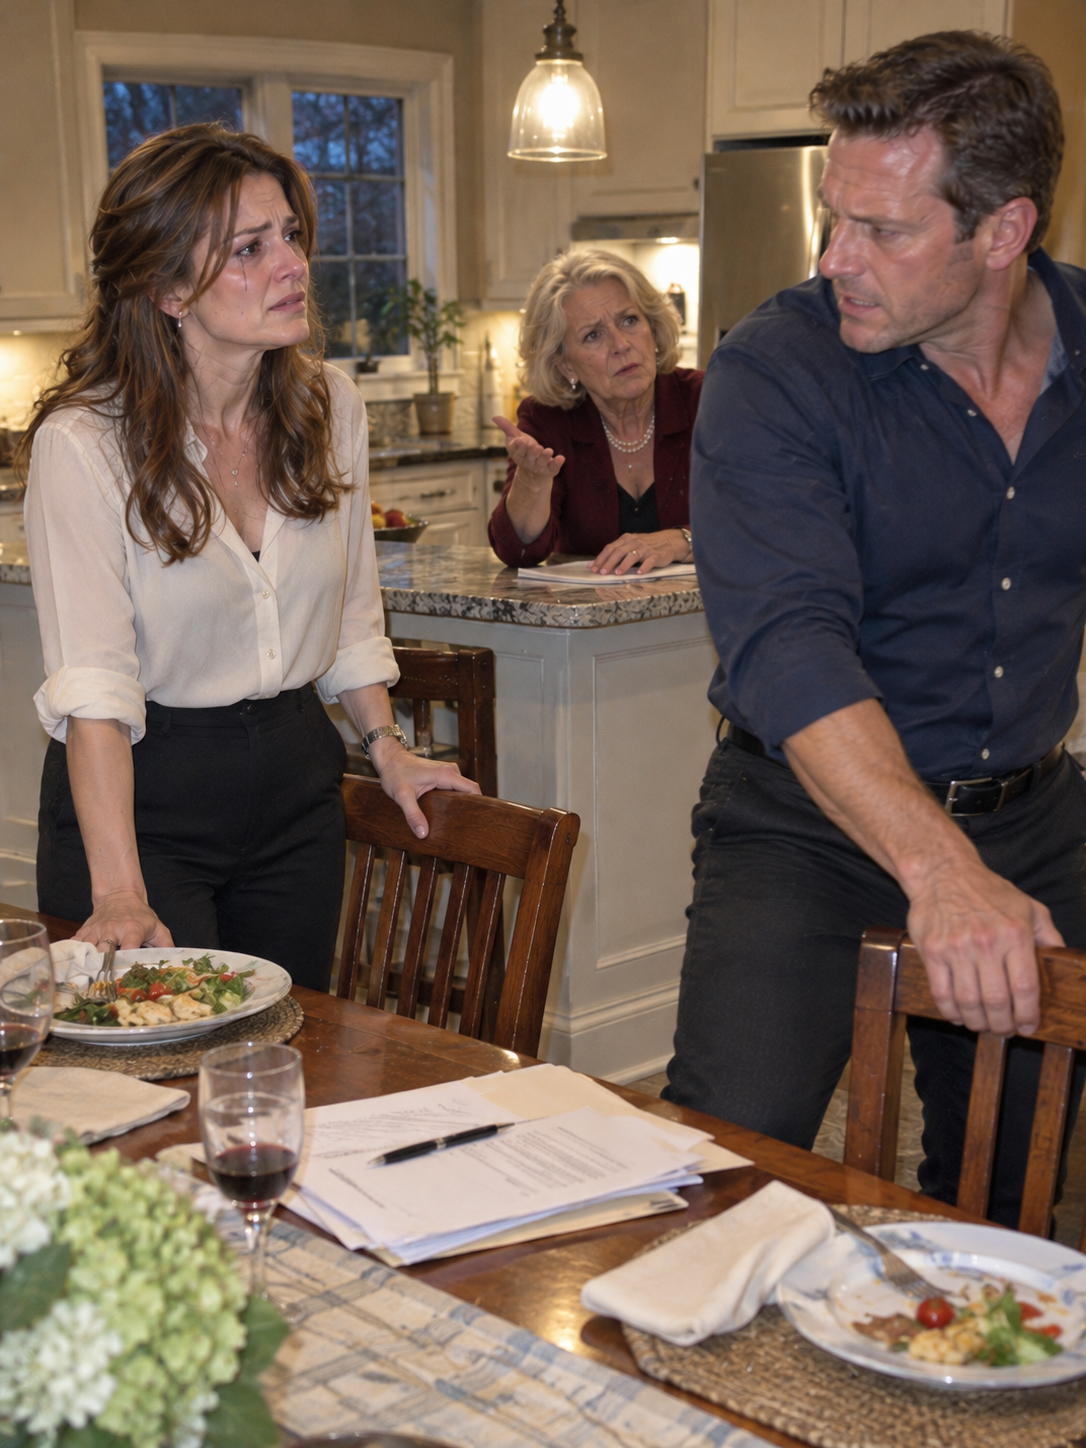
My husband texted me at 8:17 Tuesday morning, “You’re cut off. Don’t contact me again,” because I wouldn’t sign a personal guarantee for his proposed $5 million business loan. I answered, “Okay.” He thought I would panic and apologize like I always had. Instead, I called my attorney. Before noon, his business lawyer was urgently trying to reach me, and Michael had begun learning what my signature was really worth…
At 8:17 on a Tuesday morning, my husband sent me a text that said, “You’re cut off. Don’t contact me again.”
I was standing in our kitchen in Charlotte, North Carolina, holding a cup of coffee that had gone cold. Across the street, a neighbor was hauling a trash bin back to the garage. Nothing outside had changed. Inside, after fifteen years of marriage, I read those words three times before I typed the only answer I could manage.
“Okay.”
My name is Elizabeth Carter. I was forty-four that October, and until that morning I had believed that my husband and I still wanted the same future. We were preparing to buy a larger house outside Charlotte. The purchase documents sat on our dining table, along with papers connected to a loan Michael wanted for his construction company. Those papers had caused our argument the previous night.
Michael was proposing to borrow five million dollars to expand into bigger commercial projects. He had spoken about new crews, equipment, and contracts with the same bright confidence that first attracted me to him. But the lender wanted a personal guarantee. Specifically, he wanted me to sign one, putting my own financial security behind obligations I hadn’t been given enough information to assess.
I asked him to show me the full loan terms, updated company statements, and the contract supporting his projected revenue. He stared as though I’d questioned his character instead of asking a business question.
“You’ve helped with my books for years. You know how this works.”
“I know the records I’ve seen,” I answered. “I need to understand what I’m agreeing to.”
He pushed his chair back. “My own wife doesn’t believe in me.”
His mother, Diane, was sitting at the kitchen island. At seventy-three, she could make a cutting remark sound like helpful advice. “A wife should stand behind her husband,” she said.
“A wife should know what she’s standing behind.”
Michael walked out of the conversation. The text the next morning was evidently his way of finishing it. Still, for several minutes after I answered, I expected a call. He sometimes said harsh things when he felt cornered. I thought he might tell me he needed time or admit he’d gone too far. My phone stayed silent.
When we met, Michael was thirty-four and operated his construction company from a little rented office. He had two desks, an unreliable printer, and more plans than available money. I was a bookkeeper who understood how easily enthusiasm could outrun cash flow. He used to smile while I sorted his receipts and tell me I’d make an excellent detective and a terrible suspect.
We ate takeout on folding chairs in those days. He would describe the buildings he hoped to renovate, and I would ask how he planned to pay the people doing the work. He listened then. Or perhaps the risks seemed smaller when both of us had less to lose. I liked that he dreamed. I loved that he seemed to want me beside him while he built those dreams.
As his business grew, I helped with invoices and payment records after completing my own work. I eventually built a stable bookkeeping business of my own. When his cash flow was tight, my income covered more household bills. I paid for trips, organized due dates, and handled practical problems that Michael was too busy to address. He became an authorized user on two credit cards connected to an account I controlled.
It started as teamwork. Over time, it became the assumption that if a bill arrived, a vendor complained, or Michael needed a document, Elizabeth would solve it. He enjoyed telling acquaintances he’d built his company himself. I didn’t need public credit for every hour I’d helped him. I did need him to recognize that my time and money weren’t an unlimited emergency reserve.
Diane made that more difficult. At Sunday dinners she praised Michael’s ambition and hinted that cautious women could hold their husbands back. He usually kept eating while she talked. Once she said I was lucky to have a man with vision. I answered that I supported him, and she suggested support meant being less nervous about risks. I learned to change the subject rather than ask Michael to defend me again.
One evening she told me that supporting a man with vision required faith in his instincts. I remember clearing the plates afterward and thinking how strange it was that his instincts deserved admiration while my experience with accounts was treated as nagging. Michael came into the kitchen, kissed my cheek, and asked whether I had paid an invoice for him. I said yes. We never returned to what his mother had said.
The new house showed just how far the pattern had spread. We’d spent months touring properties around Charlotte, debating garages, guest rooms, and what we could comfortably afford. I wanted a manageable mortgage and a place for ordinary weekends. Michael imagined a bigger office, room for his equipment, and gatherings for his business contacts. Diane talked about a first-floor suite where she could live as she got older.
I thought that last idea was something she hoped for. Michael never asked me to approve it. I had put a substantial amount toward the proposed purchase because I believed we were choosing the house together. Only lately had I noticed that the more decisions they discussed, the less often anyone asked what I wanted.
By 8:41 that morning, I was tired of wondering whether a threat meant my marriage was over. I called Rebecca Collins, an attorney I’d consulted on a business contract two years earlier. Rebecca was practical and careful with words. She listened to the argument, Michael’s message, and my concerns about the house before asking one direct question.
“Have you signed the personal guarantee?”
“No.”
“Then don’t sign anything until we review it. And don’t cancel contractual obligations or move money just because you’re angry. Protecting yourself and retaliating are different things.”
I told her I didn’t want to hurt Michael. She replied that she was trying to make sure I didn’t hurt myself. Then she asked me to bring the house agreement, credit-account records, and whatever financing correspondence I had.
When I mentioned that Diane assumed she would be moving into the new house, Rebecca paused. “Did you agree to that?”
“No. Michael called it our future.”
“Then let’s find out exactly what you signed.”
At 9:05 I was in her office, watching her sort my papers into three piles. We began with the credit cards. I was the primary account holder; Michael’s cards were authorized-user cards, not accounts belonging independently to him. Rebecca explained that I could ask the issuer to remove that authorization, subject to its terms. She warned me not to interfere with his separate accounts or confuse being married with owning everything he used.
Next came the house. Rebecca examined the withdrawal conditions and deadlines. It wasn’t possible to erase an agreement simply because I regretted the purchase. There could be costs, disagreement about the deposit, or money I wouldn’t recover. My stomach tightened as she explained how much remained uncertain.
I had worked hard to save my contribution. The idea of losing even part of it hurt. But moving forward with a larger mortgage and a living arrangement I’d never approved could cost me more. Rebecca told me I didn’t have to decide that morning. I looked at the documents, thought about Michael’s text, and asked her to send the withdrawal notice through the proper process.
Finally, we reviewed the proposed five-million-dollar loan. Michael had spoken as though my signature was the last routine step. Rebecca pointed out that expecting my guarantee was not the same as receiving it. We prepared a factual statement making clear I had never agreed to guarantee the debt and did not intend to do so. She advised that any clarification requested by the lender should go through proper legal channels.
I left with copies of the notices and a warning not to answer heated calls impulsively. I wasn’t celebrating. The house might cost me money, and Michael’s business financing was still uncertain. But for once, the uncertainty wasn’t a reason to agree before I’d read the details.
At 10:14, sitting in my parked car, I called the credit-card issuer. After verifying my identity, the representative confirmed Michael’s authorized-user cards could be canceled. I asked her to do it and wrote down the confirmation number. The call was brief. When it ended, my hands shook.
I remembered Michael joking that he never needed to carry a wallet because I had everything covered. I’d laughed at that joke for years. Now it sounded different. There were limits to what I could keep covering, especially after he’d announced he wanted no contact with me.
At 10:37, our real estate agent acknowledged the withdrawal notice. The seller would review it, she said. She made no promise that we’d recover the deposit. Minutes later, Michael called. I let it ring. Then came a text: “What did you do to my card?”
I explained briefly that I’d removed his authorization on my account. He replied that a payment had been declined in front of a supplier and I’d embarrassed him. He didn’t mention the morning’s message or ask how I was. The embarrassment, not the threat he’d made to our marriage, was what he wanted to discuss.
I considered reminding him that he’d ordered me not to contact him. But that would start another argument, so I put the phone away. I drove home with the folder beside me, aware that each decision I’d made would have consequences I couldn’t yet calculate.
At 11:18, I was reviewing the house paperwork when a message appeared from Thomas Reed, Michael’s business attorney. Thomas had always been formal when we’d met at company functions. He had never texted me personally before.
“Elizabeth. We have a serious problem. Please contact me as soon as possible.”
I felt frightened. Had Michael already told the lender I was backing the loan? Was the house purchase more complicated than Rebecca knew? I called her instead of Thomas. She told me to forward his message and let the attorneys establish the facts before anyone drew conclusions.
Then Michael texted again. “The bank wants to know why you won’t guarantee the loan. What exactly have you told them?”
I hadn’t called the bank to accuse him of anything. I’d only refused a financial commitment I hadn’t made. I forwarded that text too. By noon, my phone showed eighty-nine missed calls, including Michael, his attorney, the real estate agent, and unfamiliar numbers. I sat looking at the screen. For fifteen years everyone had expected me to answer, find the document, make the payment, or smooth out the problem. Now they were urgently trying to reach the woman Michael had told not to contact him again.
And I still didn’t know everything he’d promised on my behalf.
CHAPTER 2
I listened to Michael’s first voicemail in my home office. He said the situation had gotten out of hand and I needed to fix it with the bank before anyone got the wrong idea. There was no apology. Rebecca advised me to keep forwarding the messages and let her communicate with Thomas. We knew the lender wanted clarification, not precisely what Michael had told them.
As I reviewed records, old warning signs took on new meaning. Suppliers had started requesting faster payment, a subcontractor invoice had remained unsettled, and Michael kept expecting customer money “next week.” His crews were working, but a company could be busy and still face a cash shortage. I didn’t know its complete financial position, and I refused to guess.
The real estate agent reported that Michael wanted to proceed with the house without me. Then Margaret, a longtime family friend, called to say I was overreacting to a single angry text. I explained the proposed guarantee, my request for documents, and the distinction between his right to run a business and my right to refuse its risks. She sounded disappointed. So was I.
Diane called that afternoon, furious that Michael’s card had been declined in front of a supplier. Then she complained about a salon appointment he’d promised to cover. I told her those were arrangements she needed to discuss with her son. It was the first time I’d ended one of our conversations without offering to solve her problem.
Later, Karen from Michael’s office called. Vendors were asking about outstanding payments, and staff were nervous about planned work. She hadn’t heard of a missed payroll, and I was grateful she didn’t embellish what she knew. But she’d heard Michael discuss my financial support as though it were settled. I began to understand why my refusal had caused such alarm.
Rebecca confirmed that the lender wanted written clarification of my position and updated financial projections, including information about a significant unpaid customer receivable. There was no finding of fraud and no final decision about the loan. There was simply a financial proposal that had counted on a guarantee I had never given.
That evening I found myself worrying about the employees I knew by name. Their families relied on their wages; they had done nothing wrong. Karen had been careful not to exaggerate, and I tried to be equally careful. I wanted them to keep working. But a guarantee could expose my savings if the company could not repay the money. Concern for the workers did not make me qualified to promise five million dollars.
The next morning I returned to my own bookkeeping clients, work I’d too often interrupted to handle Michael’s business. Then an old spreadsheet attached to Michael’s email caught my eye. It outlined expenses for our proposed new house, including groceries, utilities, transportation, and a monthly allowance for Diane. It treated her ongoing support as an established household obligation. I had agreed to none of it.
I printed the email for Rebecca. Later, she reviewed part of the loan proposal. It listed my personal guarantee as a condition expected before closing, not as something already signed. That mattered. Michael hadn’t obtained the financing, and I hadn’t taken approved money away from him. The lender still had to decide whether the business supported the loan without me.
Thursday morning I took my contribution records and original documents to Rebecca’s office. She again explained the possible costs of withdrawing from the house purchase. Then she said Thomas wanted a meeting that afternoon, with Michael present. I agreed to attend, knowing one thing had changed: I would listen to the discussion, but I wouldn’t sign my future away to end an uncomfortable conversation.
CHAPTER 3
Michael was already waiting when Rebecca and I entered Thomas Reed’s conference room. He looked tired and said he wished we could have settled things without attorneys. Rebecca reminded him that Thomas had requested the meeting. Then we addressed the guarantee directly.
“I have not signed one,” I said, “and I won’t provide one.”
Michael insisted I understood what he’d invested in his company. I told him I did, but knowledge of his sacrifices didn’t require me to assume a five-million-dollar liability. He asked whether I would let his company suffer over one angry text. I said the text was not the loan’s financial problem, and protecting myself wasn’t a punishment.
When we turned to the house, I showed him the budget that quietly included Diane’s living expenses. He said the larger home was for our family and his mother needed help. I wasn’t disputing that. I was asking why my money had already been assigned to a future nobody had discussed with me. He had no easy answer.
Thomas said the lender needed updated projections and information about the unpaid customer receivable. No one promised the loan would proceed. Near the door, Michael asked me to dinner. I agreed to consider it because I still cared about the man I’d married.
We met that evening at a steakhouse near SouthPark. He’d brought white roses. For a moment, sitting across from him felt like one of our ordinary date nights. He said he was sorry for his text, though I had to ask him to explain what he was apologizing for. At first he described how pressured he had felt, as though pressure itself were the apology. When he finally said he was sorry for telling me never to contact him, I thanked him. I wanted to take that small step seriously. Almost immediately, he brought up the loan.
“Tell me what you want for our future,” I said.
He described a growing company, the new house, family gatherings, and Diane being comfortable. When I asked what he thought I wanted, he struggled to answer. Eventually he said security and appreciation. Those were true, but neither could be restored with roses and a promise made under pressure.
He asked me to reconsider the guarantee. I refused. He argued that signing earlier would have prevented the trouble. I pointed out that the risks would still exist; I’d simply be responsible for them. When his card was declined at the end of dinner, he used another and handled the payment. I didn’t intervene. Outside, he asked whether he could come home. I said our house was still his home, but I needed space, and I needed to know whether he wanted a partner or simply someone who would keep financing his plans. He called the question cruel. I told him it was a question I had avoided for years. I drove away alone.
The following day Rebecca accompanied me to the lender’s review meeting. Ms. Parker, the representative, asked me to confirm whether I’d agreed to guarantee the debt. I said no. She recorded that and explained that the bank needed updated cash-flow figures, support for the outstanding receivable, and a repayment plan without my guarantee.
The bank made no final decision that day. Michael might have to postpone expansion, change planned spending, or negotiate different financing. At the elevators he said I’d made everything harder. I answered that signing something I couldn’t responsibly accept might have made that morning easier and my future much harder. I went home without offering another solution. I did not want the company to fail. But the lender was asking ordinary questions, and my refusal was not proof I lacked love. For the first time, I was allowing him to face a business problem as the person responsible for running his business.
CHAPTER 4
Three weeks later, Rebecca sent an update. The lender had not approved Michael’s original financing proposal. It wanted a revised plan reflecting the company’s actual cash flow and a structure without my guarantee. The business was still operating and its employees were still working, but Michael’s hoped-for expansion would wait while he addressed the lender’s questions.
The house purchase had been ended through negotiated terms. We didn’t recover everything we’d expected, and the costs hurt. But I was no longer tied to a larger mortgage, arrangements for Diane’s support, or a loan guarantee I’d never understood well enough to accept. Rebecca reminded me that the financial outcome didn’t decide whether the marriage could be saved. That question belonged to Michael and me.
When I looked at an old photograph from a friend’s wedding, I couldn’t pretend our fifteen years had all been unhappy. There had been trips, laughter, ordinary meals, and kindness when one of us was sick. Those memories were real. So was the long habit of treating my help as an entitlement. The marriage had not been one unbroken string of disappointments. That was what made the choice difficult. A single apology could not erase years of assumptions, but neither could my anger erase every good thing we had shared.
Michael asked to meet at a coffee shop. He had remembered how I took my coffee, black with one sugar. He told me he’d submitted revised figures, was reconsidering equipment purchases, and was speaking directly with his project managers. He didn’t blame me. Then he offered a fuller apology.
He admitted that when I questioned the loan, he hadn’t wanted to face the possibility that his numbers wouldn’t work. He wanted me to make the pressure disappear. He’d also stopped asking whether I could afford the help he expected. When I asked why he’d sent the text, he gave an answer that hurt more than his earlier excuses.
“I wanted you to panic,” he said. He’d hoped I’d fear losing him and agree to sign.
I told him I couldn’t build a marriage around the threat of losing someone’s love whenever I said no. He asked if we could try again. I said I didn’t know. We would need honesty about money, boundaries with Diane, shared decisions, and counseling. We agreed to continue living separately while we explored whether those changes were possible. The attorneys would handle the financial matters.
Over the following months I gave my own business proper office hours. I stopped interrupting client work whenever Michael needed a favor and began taking Saturday walks with a friend at Freedom Park. Michael and I attended counseling. Some conversations were promising; others showed how much resentment and distrust had collected over the years. Eventually, we chose to proceed with separation rather than promise a reconciliation neither of us could sustain. I was sad when we reached that decision, even though I knew it was sensible. We had once planned a house where our families could gather. Now I was planning ordinary days in which I could decide for myself when to work, rest, and answer the phone.
Even Diane called and admitted they’d grown accustomed to me carrying the load. She didn’t offer a complete apology. I didn’t demand one. Michael kept working through his company’s financial problems without my managing them. I hoped he succeeded, especially for his employees, but I no longer measured my worth by his results.
Sometimes I still remember the cold coffee beside my phone at 8:17 that Tuesday. “You’re cut off,” he’d written, expecting me to beg for a place in his plans. I didn’t stop loving him all at once, and choosing a separate life wasn’t painless. I simply learned that I could care about him without surrendering my judgment, my savings, or my right to say no. That was the future I finally chose for myself.
THE END. I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please leave a comment, like, and share the post. Thank you for reading! ❤️