My parents let me pay their $2,000 mortgage for five years, then I found a trust leaving our family home entirely to my younger brother.
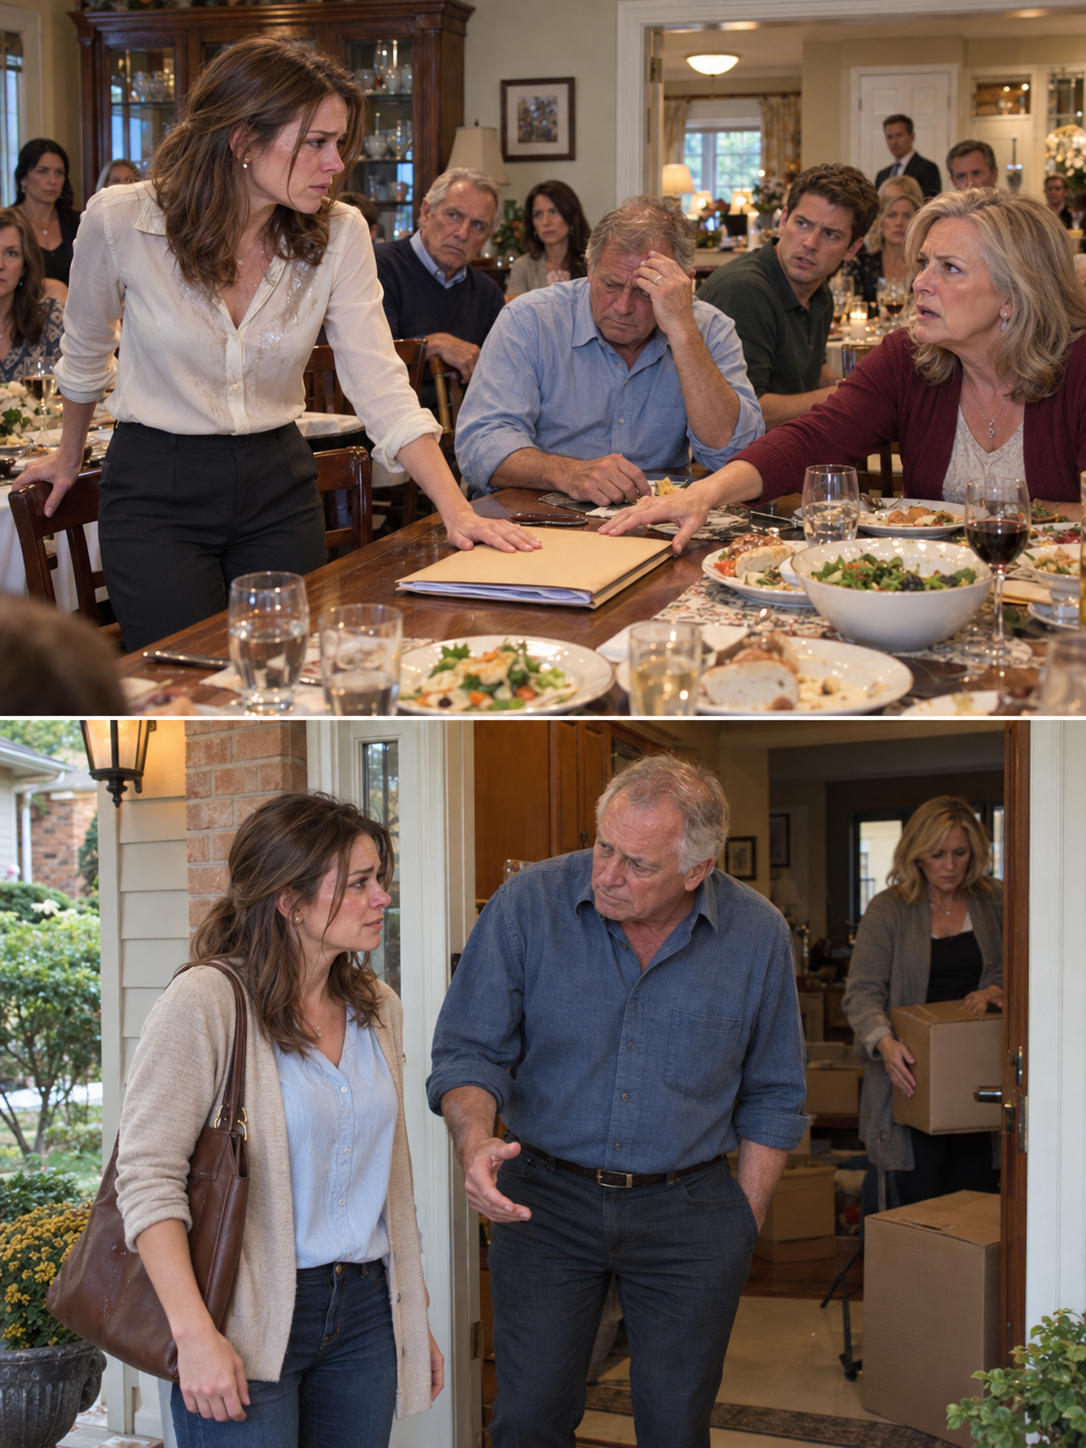
My parents let me pay their $2,000 mortgage for five years, then I found a trust leaving our family home entirely to my younger brother. When I stopped paying, Mom demanded I co-sign a new mortgage and warned that everything would collapse without me. I nearly believed her until I read the second page of the application and saw what they actually planned to do with the money…
At 8:12 on a Thursday morning, my mother sent me a mortgage application with an empty signature line circled in yellow. Her text said, “We need you to co-sign today.” By noon I had fourteen missed calls, messages from relatives I hardly heard from, and a voicemail from my father warning that the family could lose its house. Nobody was asking whether I could afford the risk. They were telling me to sign.
My name is Sarah Mitchell. I was twenty-eight, working hard at a career that had finally begun to pay well, and I had already spent $120,000 helping my parents keep their home. I thought that money was protecting something we all shared. Then I discovered a signed trust that left the house to my younger brother, Evan, and deliberately excluded me. When I asked why, my parents acted as though reading their own paperwork was a betrayal.
The house was on Willow Creek Drive, a four-bedroom place with a big kitchen and a converted garage where Dad stored records for his barber shop. My parents, Robert and Mary Ann, bought it while I was in middle school. Every holiday seemed to happen in that kitchen. There were birthday dinners, relatives arriving with casseroles, and family conversations that ran long after everyone had finished eating. Mom always called the house the center of our family. I believed her because, for most of my childhood, it was.
Five years earlier, Dad’s barber shop began struggling. A newer shop opened nearby, the rent on his business space increased, and longtime customers stopped coming as often. Mom worked part-time as a receptionist, but her checks mostly went toward utilities and groceries. They didn’t tell me everything at once. First Dad mentioned business was slow. Then Mom worried aloud about the mortgage. Eventually they invited me to the kitchen and admitted they couldn’t keep up with the $2,000 monthly payment.
I was twenty-three and had just received a promotion. I lived in a modest apartment and, for the first time, could imagine saving real money. Dad said he needed temporary help until the shop recovered. Mom promised they’d repay me when things improved. I loved them. I remembered the sacrifices they’d made raising us, and I wanted them to stay in the house where our family had celebrated so much. I agreed to cover three payments.
Three months became six. Then a full year passed. Whenever I suggested ending the arrangement, another expense appeared: an equipment problem at the shop, a repair at home, or a stretch of unexpectedly thin income. My parents never issued a formal demand, but they reminded me how frightened they were of losing everything. I sent another payment. Eventually the transfer became as routine as my own rent, except that my name wasn’t on their mortgage or deed.
The amounts were simple. Two thousand dollars a month, twelve months a year, for five years. Sixty transfers. Exactly $120,000 before the water heater, household repairs, and occasional emergency money. It was more than I’d managed to save for myself in that period. Dad called it protecting our future. Mom said the property was a family asset and that what I contributed would someday come back to me in a meaningful way. I didn’t ask her to put that assurance in writing. I trusted her.
When people at work congratulated me on my promotion, I smiled and said I was lucky. None of them knew how little of the raise actually reached my savings account. I was earning good money but living as though one unexpected bill might put me behind. And every month, I wondered whether Dad’s business would finally improve enough for me to stop sending money.
My brother Evan had an entirely different relationship with money. He was twenty-five, charming, funny, and sometimes helped at Dad’s shop. When he wanted a newer car, our parents assisted with the down payment. When he talked about opening his own grooming business, they praised his initiative and discussed ways to support it. I suggested he contribute toward the mortgage if he was going to benefit from the house too. Mom told me he was still finding his direction. Apparently being financially established meant I was supposed to carry the weight for both of us.
I postponed moving to a better apartment, reduced my retirement contributions, and turned down trips with friends. None of that felt noble at the time. It felt like ordinary budgeting around a family obligation. Sometimes I’d look at an apartment listing or a weekend getaway, then remember the next transfer and close the page. I told myself I was fortunate to have enough income to help. I also told myself that families took turns being the strong one. I didn’t notice that my turn never ended.
The discovery came on a Saturday that should have been unremarkable. Mom asked me to find a property insurance statement in the filing cabinet in the converted garage. An insurance representative wanted a document, and nobody remembered which folder held it. I knew Dad’s filing habits well enough to help. I pulled out insurance papers, utility statements, and a blue envelope marked “Mitchell Family Living Trust.” I wasn’t looking for a secret. I was looking for proof of coverage.
Both my parents’ signatures were on the trust. The date was May 17, 2023, almost two years after I’d begun paying their mortgage. I turned to the section naming beneficiaries. After both my parents died, Evan Mitchell would receive the remaining trust property. The attached schedule included the house on Willow Creek Drive. I went back through the pages searching for my own name, thinking there had to be another provision or a page I had missed.
I found one sentence stating that they had intentionally made no provision for their daughter under the trust. I read it twice, then once more. It wasn’t a clerical omission. The signatures were notarized. My parents had decided that Evan would inherit the home while I was helping pay for it, and they had continued speaking to me about a shared family future. They had every right to decide who inherited their property. What I couldn’t accept was being kept uninformed while my earnings helped preserve something they knew would not be mine.
I stood there a few minutes longer, holding the envelope carefully by its edges. The blue cover had been filed with other ordinary records, not locked away or hidden behind a false name. That almost made it worse. The decision was an established fact in their household, while I had been making plans based on an assurance that was already untrue.
I photographed the relevant pages, returned the envelope, and found the insurance statement. Mom smiled when I handed it over. “See? I always know I can count on you.” For years those words had made me feel valued. Standing there, I heard something else: she had become so sure I would help that she no longer considered whether I had been told the truth. I didn’t confront her in the garage. I needed time to think without somebody explaining away the sentence I’d just read.
That evening I pulled up my bank history and counted every mortgage transfer. Seeing sixty payments lined up on the screen made the cost feel different from the monthly number. It was the down payment I hadn’t saved. It was years of retirement contributions I hadn’t made. It was a future I’d delayed while Evan’s was being protected. I printed the transfers and put them beside the photographs of the trust. The numbers were not a feeling I could be talked out of.
On Monday I met with a real estate attorney. I showed him the trust pages, my banking records, and the original requests for three months of help. He explained that voluntary mortgage payments didn’t automatically make me an owner, and being excluded from the trust didn’t automatically create a right to repayment. But I wasn’t named on the loan and hadn’t separately agreed to guarantee it. I could stop future contributions. Recovering money already paid was another matter, and I wasn’t there to start a lawsuit. I wanted to know whether saying no was legally an option.
That evening I texted Mom that I’d found the trust. She first asked, “What trust?” When I identified the May 2023 document and told her I’d seen Evan’s name, she answered that it was a private family document. I asked how a document allocating the house could be irrelevant to the daughter financing it. She replied that Evan’s situation was different and I knew it. She didn’t deny the exclusion or apologize for hiding it. She wanted to talk, but only after I made it clear I was reconsidering my payments.
Wednesday evening, I canceled the automatic transfer due Thursday. My finger stayed above the confirmation button longer than I expected. I’d been trained by five years of repetition to treat that payment like a necessity. But it was my parents’ mortgage, and the choice to cover it had always been mine. I saved the cancellation receipt. The next morning Mom texted, “You’re late this month.” I answered, “Not my house. Not my bill.”
Evan called minutes later. Dad left a voicemail saying they hadn’t budgeted for the missing transfer. That told me how permanent my supposedly temporary support had become. Two days later, at Mom’s insistence, I went to the house for a twenty-minute conversation. Dad sat in the kitchen with a calculator and bills spread across the table. Mom stood beside him, her arms folded. She didn’t ask how I was doing. She asked when the payments would resume.
I put the trust document on the table and asked why they’d left me out. Mom repeated that Evan wasn’t as established as I was. Dad insisted he had never promised to put me on the deed. He was right about the deed. But both parents had called my payments an investment in our future. Then Evan walked in, invited without my knowledge, and admitted he’d known about the trust for some time. He saw nothing wrong with accepting the inheritance while I financed the mortgage. I told him they could choose their beneficiary and I could choose how to spend my salary.
Mom accused me of attacking him. Dad mentioned that they might amend the trust someday, after Evan was more secure, but he had no date, draft, or promise I could rely on. I said I would not restart the transfers. The following week, Mom sent the new mortgage application and demanded my signature. The page describing the existing debt looked ordinary enough. Then I reached the line labeled “Estimated cash to borrower”: $136,000. They weren’t merely trying to cover a missed $2,000 payment. They wanted to pull another six figures out of the house, and they wanted my income behind the debt.
CHAPTER 2
I took the application back to the attorney rather than asking my parents to interpret it. The current mortgage balance was approximately $276,000. The proposed refinancing would replace it with a much larger obligation, including closing costs and extra borrowing. Monthly payments would jump from roughly $2,000 to about $3,280. My parents had already struggled with the smaller amount, and now they wanted me responsible for something far heavier.
The supporting worksheet explained the $136,000. Approximately $72,000 was earmarked for Evan’s proposed grooming business, $38,000 for business and household debts, and $26,000 as a cash reserve. None of those amounts would create ownership for me. My signature would help the lender count my income, but it wouldn’t add my name to the deed or the trust. If my parents stopped paying, the lender could look to me for the entire debt. I could be supporting Evan’s plans long after my own savings were exhausted.
Worse, the preliminary lender notes mentioned a non-occupant co-borrower before I ever canceled the old mortgage transfer. The application process had started weeks earlier. Their emergency hadn’t appeared because I refused one payment; they had been developing a bigger borrowing plan while assuming I’d agree. When I asked Dad why he hadn’t told me, he said they knew I’d help once I understood its importance. I asked why the business money had never been mentioned. He said Evan’s company might eventually benefit everyone.
Soon the argument moved into the extended-family group chat. My cousin Leah forwarded a screenshot showing Evan accusing me of abandoning our parents because I resented his opportunities. Aunt Denise wrote about gratitude. Mom said she’d always treated her children equally and couldn’t understand my selfishness. Leah privately admitted she’d assumed I sometimes bought groceries; she had no idea I’d sent $120,000 toward the mortgage.
I posted a concise explanation with redacted transfer records and the trust clause showing my deliberate exclusion. I did not publish the private loan packet or account information. I said I wasn’t demanding the inheritance or repayment; I was ending voluntary payments. Uncle Martin asked whether the sixty transfers were real. When Mom said the documents lacked context, he asked what context could make them disappear. Aunt Denise wanted to know why Evan wasn’t contributing. He insisted everyone was missing the point, then left the chat.
The conversation spread among relatives, and Evan posted a vague complaint on a neighborhood page. Some people apologized for judging me without facts. Others scolded me for discussing family finances publicly. I agreed privacy mattered, but my mother had used the family chat to accuse me first. She called furious, then warned that the bank could take the house unless I co-signed immediately. I told her one missed payment didn’t mean an instant foreclosure and refinancing into greater debt wasn’t their only choice.
That afternoon she announced a family dinner to settle the dispute. Eleven people were invited, apparently to persuade me together. I agreed to attend but said I wouldn’t bring anything to sign. Before going, I met my best friend Alice at a cafe. She asked whether I would want the new mortgage even if my parents added me to the deed. For the first time, I answered without thinking about fairness or inheritance. No. I wanted my own financial future back.
Alice asked whether I’d saved anything for myself since stopping the transfer. I told her I’d moved the first $2,000 into a separate savings account. The number seemed small compared with the years I’d lost, but she said it was mine, and that mattered. Before leaving the cafe I checked the document history again. The loan process had started nearly three weeks before Mom’s urgent message. Dad texted asking me not to embarrass them at dinner. I wondered whether they’d invited relatives to listen or simply to outnumber me.
CHAPTER 3
At 6:45 I parked outside the house on Willow Creek Drive and saw relatives already gathered around the dining table. A lender’s folder waited beside my place setting. Mom greeted me with a tense smile and said it would be easier if everyone helped us reach an agreement. I sat down and asked what she wanted people to understand. She delivered a prepared speech about parental sacrifices and how my sudden refusal endangered the family’s home.
Evan nodded as she spoke. Dad looked tired, his hands folded near the documents. When Mom finished, I asked one question: “Did you tell everyone the new mortgage would give Evan $72,000 for his business?” The room quieted. Mom said those details weren’t appropriate for a family discussion. I looked around the table. She’d invited these people to discuss my paycheck. Why should the other numbers be secret?
Uncle Martin wanted to know what Evan’s venture had to do with the house. I explained the $136,000 cash-out, the rise to about $3,280 a month, and the proposed allocations for Evan’s business, existing debts, and reserves. I also explained that my name would be on the loan but not the deed. Evan insisted his business would benefit everyone eventually. Aunt Denise asked whether I would own any part of it. He didn’t answer.
Mom opened the folder to the signature page. “We’re not asking you to give anything up. We just need your income to qualify.” I looked at the empty line and asked whether being responsible for a much larger mortgage counted as nothing. Dad said he had always expected me to be successful enough to buy my own house. He sounded almost proud when he said it, as though my ability to manage money had made my share of the inheritance unnecessary. I wondered whether he understood that I was still renting because I’d been making their payments. When I asked whether that was why the trust excluded me, he nodded. They believed Evan needed more help.
“Then why didn’t you tell me before accepting five years of payments?” I asked. Mom’s answer was immediate: “Because we knew you’d make it into a problem.” I asked whether that meant she feared I might stop paying. She didn’t deny it. She said they couldn’t risk upsetting me when they depended on the money. Uncle Martin leaned back. Aunt Denise stared at her plate. Evan muttered that everyone was being dramatic.
Dad finally said they’d handled the trust badly and should have told me. It was the first public acknowledgment I’d heard. Mom brushed it aside, promising to discuss the past after I signed. I thought about the years I’d delayed my own savings and how much greater the risk would become if this business plan failed. I closed the folder and slid it away. “I’m not signing,” I said.
Mom asked what they were supposed to do. Evan said he couldn’t qualify for a loan that large because he didn’t earn enough. Uncle Martin answered that perhaps he shouldn’t build a business using a house he couldn’t afford to maintain. Nobody had a response. Mom began promising she would never ask for another favor. I remembered how three months of help had lasted five years.
I opened the group chat and sent the sentence I’d written earlier: “You chose Evan to inherit the house, so ask Evan to sign for the mortgage.” Phones lit up around the table. Evan pushed his chair back; Mom stared at me. Ownership had been promised to him, but risk was being assigned to me. I thanked everyone for hearing the facts and left the application untouched. I didn’t wait for another vote on what I was allowed to do with my own income.
CHAPTER 4
That night Mom texted that she hoped I was satisfied with what I’d done to the family. I didn’t answer. The refinance couldn’t proceed without another qualified applicant, and the lender’s deadline passed. Despite the warnings I’d been given, the house wasn’t seized because of one missed payment. My parents used savings to catch up, but their finances had been strained long before I canceled the transfer.
In the months that followed, they had to face expenses my payments had concealed. The proposed expansion for Evan’s business fell apart without the borrowed money. He lost a deposit on commercial space he had reserved too early and eventually took full-time work at another grooming shop. Dad scaled back his barber shop and began renting a chair elsewhere rather than maintaining the entire business. Mom increased her working hours. Those choices were uncomfortable, but they belonged to the people making them.
Eventually my parents listed Willow Creek Drive for sale. Several months later it sold. They paid off the existing mortgage, settled important debts, and moved into a smaller rental they could afford without sending me a monthly request. It wasn’t foreclosure, and there was no last-minute miracle. They gave up a house they’d wanted to keep and a plan to pass it entirely to Evan. The consequence was real, but so was the chance to live within their means.
I didn’t enjoy watching them leave the house where we’d celebrated so many holidays. I remembered Dad’s accounting files in the converted garage and the kitchen where Mom had once assured me I was protecting our future. But nostalgia didn’t erase what had happened. They’d accepted my help while withholding a decision they understood might change my willingness to provide it. Then they’d tried to turn my stable income into security for a much larger loan I hadn’t requested.
Mom blamed me for a while. Evan contacted me mainly around holidays, and we never became the close siblings I’d hoped we could be. Dad eventually admitted they’d depended on my contributions too long and should have disclosed their estate plan. I appreciated the acknowledgment, but it didn’t obligate me to resume financing them. I could care about their well-being without becoming the backup plan for every choice they made.
Some relatives stayed out of it after the dinner. Others offered advice that sounded like the same old instruction to make peace. I stopped explaining my decision to people who already had the records. I wasn’t trying to convince anyone that my parents were bad people. Dad had worked hard for many years, and Mom had helped hold the family together when we were young. Those things were true, too. They simply didn’t make the new mortgage safe or the hidden trust fair.
I started saving the $2,000 each month instead. I built an emergency fund, increased my retirement contributions, and worked toward a down payment on a place of my own. The amount was familiar, but for the first time it stayed in an account attached to my future. Sometimes I thought about the $120,000 I’d already paid. I didn’t recover it. I didn’t receive an ownership interest in Willow Creek Drive, and no perfect apology arrived to make the years feel fair.
What I received was something I could act on: the knowledge that love didn’t require my signature on a loan I couldn’t safely carry. My parents were allowed to make an inheritance decision. Evan was allowed to pursue a business. I was allowed to say no to funding both. When I think of that night at the dining table, I don’t remember the folder so much as the moment I pushed it away. I had finally given my own future a place in the room.
THE END.
I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please leave a comment, like, and share the post. Thank you for reading! ❤️