A new executive slammed my personnel file onto the table and mocked my $800,000 salary in front of twelve people.
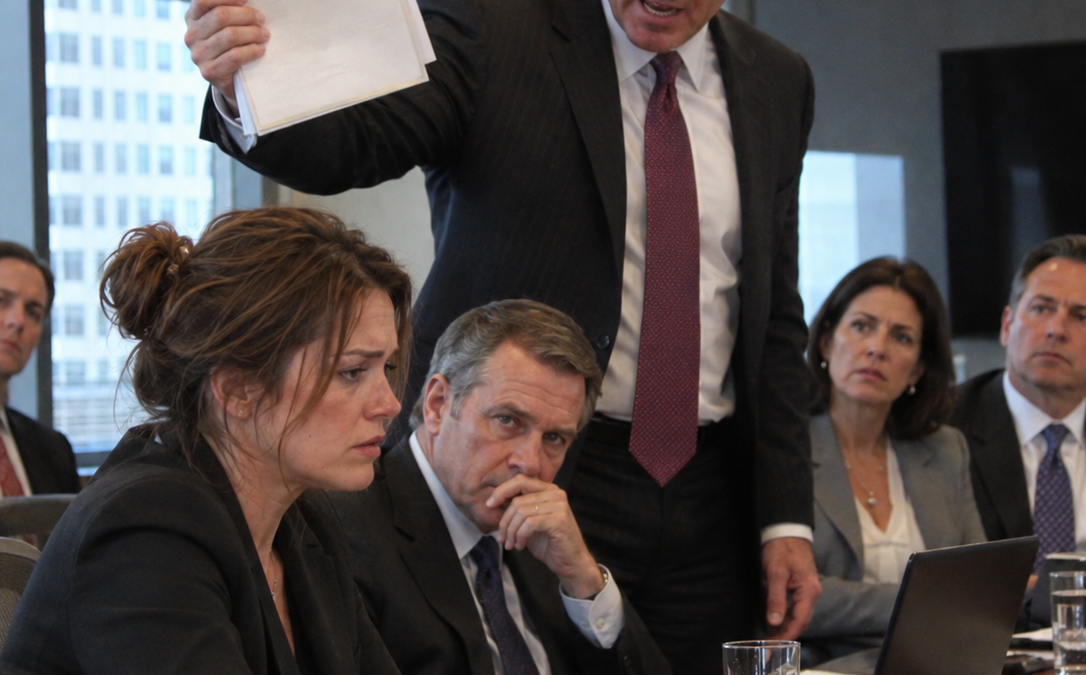
A new executive slammed my personnel file onto the table and mocked my $800,000 salary in front of twelve people. I warned him the acquisition closing the next morning could expose us to more than $2 billion. He laughed, put me on leave, and closed the deal anyway…
My name is Lisa Harmon.
For six years, I worked at Hexagon Financial as a senior compliance analyst.
My job was not glamorous.
I read contracts.
Compared financial disclosures.
Checked acquisition structures.
Looked for the sentence everyone else had skimmed past because it seemed harmless.
Most days, if I did my job perfectly, nothing happened.
That was the problem.
People noticed the disaster.
They rarely noticed the person who prevented it.
Walter Sterling had been at Hexagon for three weeks when he decided I was unnecessary.
He stood at the head of the conference table holding my personnel file.
“Are we really paying this woman eight hundred thousand dollars a year to look at codes?”
Twelve executives turned toward me.
I kept my hands flat on the table.
Walter smiled.
“I’ve been here three weeks, and I can already see the inefficiencies bleeding this company dry.”
Then he read my title aloud.
“Senior compliance analyst.”
He made it sound like a joke.
“Reports nobody reads. Emails about theoretical problems. Warnings about disasters that never happen.”
My boss, Sharon, tried to interrupt.
“Walter, Lisa’s track record—”
He waved her off.
“What track record?”
He looked around the room.
“If the catastrophes never happened, maybe they were never real.”
I had been awake since four that morning.
My daughter Tara had been sick for three days.
My son Luke had a debate tournament coming up.
My husband Carl had been carrying most of our home life while I worked sixteen-hour days trying to finish one analysis.
Quantum Ridge Holdings.
A major acquisition scheduled to close at eight the next morning.
I was tired.
And I was done being polite.
“Section twelve, subsection four.”
Walter stopped.
I continued.
“The earnout structure conflicts with the indemnification language.”
Martin Cross, our CFO, leaned forward.
I looked directly at him.
“If this closes tomorrow as written, Hexagon could face liability exceeding two billion dollars.”
Walter smiled wider.
“Two billion?”
A few people shifted.
He looked around theatrically.
“Everyone hear that?”
Then he turned back to me.
“You’re telling me our internal legal team missed this.”
“Yes.”
“Our outside counsel missed it.”
“Yes.”
“Three advisory firms missed it.”
“Yes.”
“But you found it.”
“Yes.”
He laughed.
Martin didn’t.
“What exactly is the exposure?”
Finally.
Someone had asked.
I opened my laptop.
“Quantum Ridge is classifying certain one-time project fees as recurring subscription revenue.”
Martin’s expression changed slightly.
I continued.
“When integration begins and their reporting is reconciled under Hexagon’s accounting standards, their earnout metrics may fail.”
“So?”
“The indemnification language gives them room to argue Hexagon deliberately interfered with operations to suppress earnout performance.”
I clicked to the relevant section.
“The potential earnout is approximately four hundred million dollars over three years. Add consequential damages and shareholder-value claims, and the downside scenario becomes enormous.”
The room went quiet.
Walter shook his head.
“This is exactly what I mean.”
He turned to Martin.
“Hypothetical catastrophes.”
Then back to me.
“You build worst-case scenarios and call them analysis.”
“Delay closing seventy-two hours.”
I kept my voice level.
“Have independent counsel review the conflicting language and verify Quantum Ridge’s revenue-recognition methodology.”
Walter did not even look at the document.
“When does the deal close?”
Martin answered.
“Eight tomorrow morning.”
Walter nodded.
“Then it closes at eight tomorrow morning.”
He looked at me.
“And Lisa, take two weeks of paid leave.”
Sharon stared at him.
“Walter—”
“Rest.”
He closed my personnel file.
“Think about whether this role is really the right fit.”
Everyone knew what that meant.
Paid leave.
Then a performance plan.
Then an exit package.
I walked back to my office knowing my career at Hexagon was probably over.
Ten minutes later, Sharon appeared.
“I’m sorry.”
“You tried.”
“He’s been targeting expensive positions since he arrived.”
I looked at the Quantum Ridge documents still open on my screen.
Yellow highlights.
Red flags.
Six weeks of warnings.
“What are you going to do?”
I opened a blank email.
“Document everything.”
For the next two hours, I wrote the most important email of my career.
No anger.
No accusations.
Only facts.
Contract sections.
Revenue discrepancies.
Dates of prior warnings.
Potential exposure.
And one recommendation:
Delay closing for seventy-two hours pending independent review.
I sent it to Martin.
Copied Walter, Sharon, and General Counsel Philip Strauss.
Eighteen minutes later, Walter replied.
Two sentences.
Noted. Closing proceeds as scheduled.
I stared at the message.
Then I preserved the complete chain with my attorney later helping ensure I retained only records I was legally entitled to keep for my own employment dispute and professional protection.
At the time, all I knew was that if Quantum Ridge failed exactly the way I expected, nobody was going to say I had stayed silent.
The next morning, at 8:17, the company announcement arrived.
Hexagon Financial had officially acquired Quantum Ridge Holdings.
The deal was done.
The countdown had started.
THE NEXT PART IS BELOW 👇 Don’t forget to switch from “Most Relevant” to “All Comments” to continue reading more 👇
IF FACEBOOK BROUGHT YOU HERE, HERE’S THE CONTINUATION YOU’VE BEEN WAITING FOR. ENJOY!
I spent the first night of my leave sitting at the kitchen table.
Two in the morning.
Laptop open.
Checking the same numbers again.
And again.
What if Walter was right?
What if I had become the analyst who saw danger everywhere?
Carl found me staring at the screen.
“How many times have you checked it?”
“I don’t know.”
“Different answer yet?”
“No.”
He pulled out a chair.
“Then you did your job.”
“It doesn’t feel finished.”
“You warned them.”
“They’re still closing.”
“That part isn’t your decision.”
He was right.
But responsibility is strange when you’re good at spotting risks.
You can know intellectually that somebody else made the decision and still feel the consequences coming toward you.
The second day of my leave, I called Sharon.
“I’m resigning.”
Silence.
Then:
“Lisa, don’t.”
“He’s going to terminate me anyway.”
“You’re still being paid.”
“For two weeks.”
“You have two kids and a mortgage.”
“I also have six years of work I’m not letting Walter rewrite.”
That was what frightened me most.
Not unemployment.
The narrative.
If I stayed, Walter could gradually turn me into the difficult employee who resisted change.
The expensive analyst who saw theoretical problems everywhere.
The woman who simply couldn’t adapt to new leadership.
If I left on my own terms, my resignation would say something much simpler.
I disagreed with a major risk decision.
I documented it.
And I left.
That afternoon, I resigned.
Brief.
Professional.
Effective immediately.
Then I called an employment lawyer named Simone Pacheco.
She listened without interrupting.
When I finished, she asked:
“Do you have documentation showing when you raised the Quantum Ridge concerns?”
“Yes.”
“Responses?”
“Yes.”
“Anything showing you recommended a delay?”
“Yes.”
She paused.
“Good.”
Not because a lawsuit was guaranteed.
Not because my employer had necessarily committed some automatic legal wrong.
Because documentation meant facts would be harder to rewrite later.
She helped me preserve the records properly and separate company-confidential materials from what I could legitimately use to establish my own timeline.
Then we waited.
For the first week after resigning, life felt almost normal.
I attended Luke’s debate practice.
Took Tara to the doctor without rescheduling.
Cooked dinner.
Slept more.
Recruiters began calling.
Senior compliance professionals with large-acquisition experience were in demand.
I had interviews.
Options.
Still, part of me remained inside Quantum Ridge.
Waiting.
Eight days after I left, Sharon called.
“Integration starts next week.”
“How does it look?”
“Fine so far.”
So far.
Exactly two weeks after the acquisition closed, my phone rang at eight Saturday morning.
Sharon.
Her voice was shaking.
“Lisa.”
I walked out of the kitchen.
Carl was making pancakes with the kids.
“What happened?”
“You were right.”
My knees went weak.
“About what?”
“All of it.”
Quantum Ridge’s financial reports had begun arriving.
Once Hexagon’s finance team tried to reconcile the acquired company’s reporting under standard internal practices, the revenue classifications stopped making sense.
One-time project charges had been treated as recurring revenue.
Implementation fees were showing up in categories suggesting longer-term subscription performance.
The numbers supporting the acquisition valuation were weaker than the headline figures had suggested.
Then came the second problem.
Quantum Ridge’s lawyers sent a demand.
They claimed Hexagon’s post-acquisition integration had interfered with the company’s ability to meet the earnout targets.
And they cited the same indemnification language I had flagged.
“How much?”
Sharon hesitated.
“Two point one billion.”
I sat down.
Almost exactly the exposure I had modeled.
“Where’s Walter?”
“Emergency board meeting.”
“Has my name come up?”
Another pause.
“Yes.”
Of course it had.
Martin remembered my email.
So did Philip.
Walter reportedly tried to describe my warning as one more theoretical concern.
Martin asked for the documentation.
There was a lot of documentation.
I called Simone.
She answered on the second ring.
“It happened.”
“How bad?”
“Two-point-one-billion-dollar claim.”
“Do not respond to anyone at Hexagon directly.”
By Monday morning, my inbox was full.
Martin.
Philip.
HR.
Then Walter.
Need to discuss Quantum Ridge matter urgently.
I forwarded everything to Simone.
Tuesday afternoon she called.
“They want you back.”
I laughed.
“As an employee?”
“No.”
“A scapegoat?”
“Also no.”
She almost laughed.
“They want you as an independent consultant helping outside counsel understand the acquisition structure.”
The irony was impossible to miss.
Three weeks earlier, I was an $800,000 inefficiency.
Now they needed the expertise Walter said had no measurable value.
Simone negotiated the terms.
Full protection for my role as consultant.
Clear separation from the decision to close the acquisition.
A professional consulting rate.
And, most importantly to me, an accurate written timeline showing that I had identified the risk, escalated it, and recommended a delay before closing.
I did not want a public apology.
I wanted the record to be correct.
Hexagon agreed.
When I walked back into the building three weeks after leaving, the atmosphere was completely different.
Quiet.
Tense.
General Counsel Philip Strauss met me in the lobby.
“Thank you for coming.”
“Where do we start?”
“Conference Room A.”
The room was packed.
Martin.
Sharon.
Outside counsel.
Several senior finance people.
Walter sat at the far end.
He did not look at me.
Philip began.
“Quantum Ridge is alleging that Hexagon caused the failure of the earnout metrics after acquisition.”
He gestured toward me.
“Lisa identified material concerns with the earnout and indemnification structure before closing.”
Then:
“We need the full timeline.”
So I gave it to them.
The first clause I flagged.
The revenue inconsistencies.
The three earlier emails.
The risk memo.
Then the final email sent eighteen hours before closing.
One outside attorney stopped me.
“Who received that email?”
“Martin Cross. Walter Sterling. Sharon Reeves. Philip Strauss.”
“Who responded?”
“Walter.”
She turned toward him.
“What did you do after receiving the warning?”
Walter finally looked up.
“I reviewed it.”
“Did you ask counsel to specifically investigate the revenue-recognition issue?”
“No.”
“Did you request another analyst independently verify Lisa’s work?”
“No.”
“Did you commission supplemental due diligence?”
“No.”
“Why not?”
Walter’s jaw tightened.
“I considered the concerns theoretical and did not believe they justified delaying the transaction.”
The attorney wrote something down.
Then looked at me.
“In your professional opinion, should the deal have closed without further review?”
“No.”
“At minimum?”
“Delay closing until the revenue methodology and conflicting contract language were independently verified.”
Nothing about that answer felt triumphant.
A $2.1 billion claim was not a victory.
It threatened thousands of people who had never been in that conference room.
Employees.
Families.
Retirement accounts.
People whose only mistake had been working for a company where one executive believed confidence was more valuable than scrutiny.
For the next several weeks, I helped outside counsel and Hexagon’s finance team reconstruct what had happened.
The deeper review raised serious questions about Quantum Ridge’s pre-acquisition financial presentation.
The revenue was real in the sense that customers had paid money.
But some of the classifications used to present growth and predictability appeared far more aggressive than Hexagon understood before closing.
That distinction mattered.
Hexagon’s defense became less about:
We didn’t cause the earnout failure.
And more about:
The deal may have been priced and structured around financial assumptions that were never as strong as represented.
Lawyers handled the legal claims.
Auditors handled the accounting conclusions.
I handled the analysis I knew.
Eventually, Quantum Ridge’s $2.1 billion demand was withdrawn as part of a negotiated restructuring of the earnout terms.
The dispute ended without the catastrophic payout everyone had feared.
Hexagon survived.
Walter resigned soon afterward.
The company announcement said he was leaving by mutual agreement to pursue other opportunities.
Nobody asked me to interpret that sentence.
A few weeks later, Philip asked me into his office.
“We want you back permanently.”
He offered me a senior risk and compliance leadership role.
Direct access to the board.
A substantial salary.
Equity.
Actual authority.
Everything I had wanted while working there.
I said no.
Philip stared at me.
“You’re serious?”
“Yes.”
“Why?”
“Because I already accepted another job.”
Catalyst Partners was a specialized acquisition-risk firm.
They had contacted me while I was consulting for Hexagon.
The salary was lower than Hexagon’s new offer.
But the work was exactly what I wanted.
Independent transaction reviews.
A team built around people whose job was to challenge assumptions before deals closed.
And a culture where saying:
“Stop. This needs another look.”
was not treated like disloyalty.
My final day consulting for Hexagon, Sharon took me to lunch.
“You’re really leaving.”
“I am.”
“We’re going to miss you.”
“I’ll miss you too.”
Then I smiled.
“Catalyst is hiring.”
She laughed.
“Give me six months.”
That evening, Carl opened a bottle of wine after the kids went to bed.
“To the woman who saved a company that didn’t deserve her.”
“I didn’t save it.”
He raised an eyebrow.
“I did the job they should have let me do the first time.”
“That sounds suspiciously like saving it.”
I smiled.
But the truth was more complicated.
I was still angry.
Angry that it took a near catastrophe for people to listen.
Angry that expertise becomes invisible precisely when it works.
Angry that preventing disaster often looks, afterward, like worrying about something that never would have happened.
Then I realized that anger could be useful.
Because someone has to read the boring clause.
Someone has to compare the numbers everyone else accepts.
Someone has to ask:
What happens if our assumptions are wrong?
Three months into my new role at Catalyst, I reviewed an acquisition for a healthcare technology company.
Deep in the regulatory material, I found a reimbursement issue that could expose the buyer to major financial risk.
The client’s CEO pushed back.
His existing legal team had already reviewed the transaction.
This time, nobody laughed.
I documented the concern.
The client delayed.
Specialized counsel examined it.
Within a week, they confirmed the problem needed to be resolved before closing.
The CEO called me.
“Thank you.”
That was all.
No disaster.
No emergency board meeting.
No billion-dollar claim.
Just a transaction stopped long enough for somebody to ask the right question.
That was what success in my profession was supposed to look like.
Quiet.
Almost invisible.
Months later, Martin Cross sent me a message.
He had left Hexagon too.
He wrote:
I should have backed you more strongly in that conference room. I’m sorry.
I read it twice before replying.
Then I wrote:
You asked for the documentation when it mattered. That helped the truth come out.
Because by then, I no longer needed every person who had failed me to suffer.
I needed something simpler.
For the work to be understood.
For the record to be accurate.
For me never again to sit in a room while someone who had been there three weeks explained the value of six years of expertise back to me.
Walter once asked what measurable value I produced.
For a while, that question haunted me.
Now I know the answer.
Sometimes the value of compliance is the lawsuit that never gets filed.
The acquisition you delay.
The liability clause you rewrite.
The bad assumption you catch before it becomes somebody else’s emergency.
And sometimes the only proof of that value arrives after people ignore you.
That does not make the expertise more real.
It was real before anyone listened.
The morning Walter laughed at me, I was already right.
The $2.1 billion claim only made it impossible to keep pretending otherwise.
THE END.
I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please leave a comment, like, and share the post. Thank you for reading! ❤️