“You’re the responsible one—you can handle it.” That was my family’s attitude when my parents gave my older sister a $95,000 Tesla for her birthday, then handed me a $60,000 mortgage bill and expected me to take over their debt.
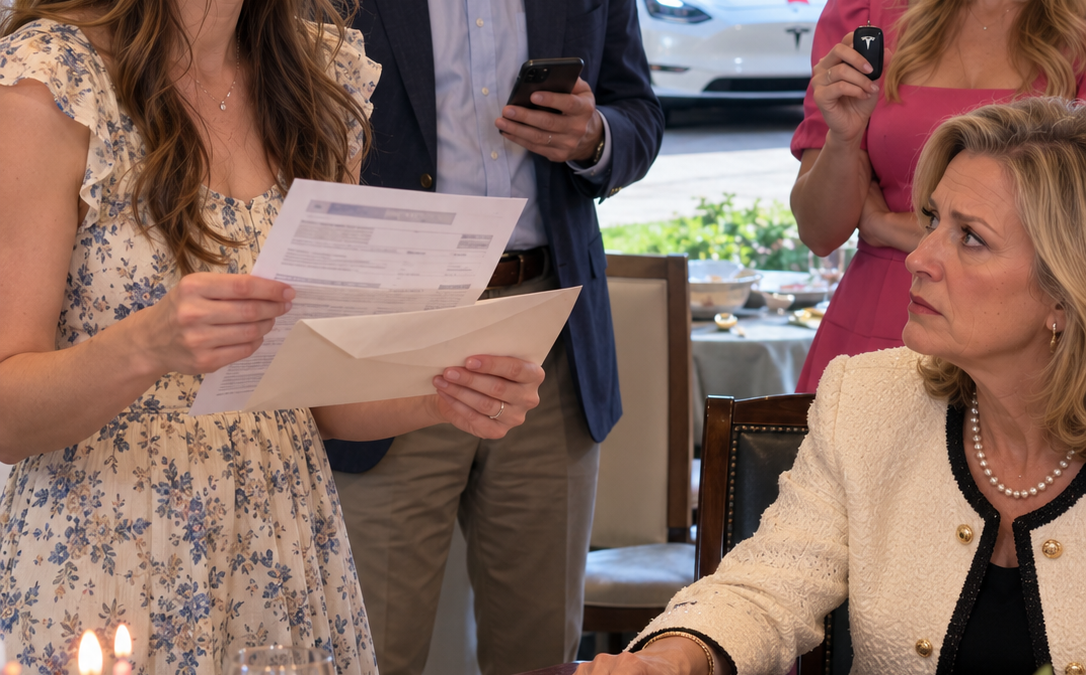
“You’re the responsible one—you can handle it.” That was my family’s attitude when my parents gave my older sister a $95,000 Tesla for her birthday, then handed me a $60,000 mortgage bill and expected me to take over their debt. I was 27, freelancing in Tulsa and had saved $30,000 by living carefully. I moved out instead. Three weeks later, my bank balance dropped to $10,000—and I discovered who had paid for Chelsea’s car…
My name is Bethany, and I was twenty-seven when my sister Chelsea’s birthday finally made me question what my place in my family really was.
The party was at my parents’ house in the Tulsa suburbs.
There were balloons, catered food, neighbors, relatives, and enough excitement to make it obvious my parents had planned something substantial.
Dad—Robert—stood at the head of the table with a set of car keys in his hand.
“This is for our star.”
Everyone followed him outside.
Parked in the driveway was a brand-new Tesla worth about $95,000.
Chelsea screamed.
People clapped while she posed beside the car, turning the keys in her hand for photographs.
I clapped too.
Chelsea had always been the one my parents enjoyed celebrating.
Growing up, she got the sparkly dresses, the Disney trips, the praise.
As an adult, she spent freely on designer bags and weekend getaways despite rarely keeping a steady job.
I was different.
I worked as a freelance marketer, picking up one project after another and trying to build a stable life without asking anyone for much.
By then, I had managed to save $30,000.
It wasn’t glamorous money.
It was late-night work, skipped purchases, and years of telling myself that eventually I would use it for a home, a business, or some kind of security.
After Chelsea finished taking pictures with the Tesla, Mom slid a plain envelope toward me.
“This is for you.”
For one foolish second, I thought perhaps my parents had planned something thoughtful for me too.
Inside was a mortgage bill.
Sixty thousand dollars.
I looked at Mom.
“What is this?”
“Our remaining mortgage obligation,” Pamela said. “You can handle it.”
Dad barely looked up from his phone.
I stared at the paper.
“You’re giving Chelsea a $95,000 car and giving me your debt?”
Chelsea laughed softly.
“Relax, Bethany. It’s just money.”
Just money.
I had spent years watching every dollar while she spent without consequence.
Now my parents were rewarding that lifestyle and assigning me the bill for theirs.
I didn’t make a scene.
Maybe I should have.
Instead, I finished the evening smiling when someone spoke to me and carrying that envelope in my purse like a weight.
Later, alone in my childhood bedroom, I took the mortgage paper out again.
The numbers looked exactly as bad the second time.
I knew the role my parents had given me.
Chelsea was the daughter to celebrate.
I was the daughter who could fix things.
That night, I packed.
By morning, I had found a small studio apartment in downtown Tulsa.
The floors creaked and the rooms were cramped, but when I signed the lease and paid the deposit, the space belonged to me.
I loaded my car with a suitcase, my laptop, and a few books.
I didn’t announce my departure.
I just left.
Mom called while I was unpacking.
I stared at her name on the screen, then blocked it.
Dad’s number went next.
A week later, a forwarded letter arrived in Mom’s handwriting.
She had addressed me as “the backbone of this family.”
I tore it up without reading the rest.
Backbone.
It was a flattering word for someone expected to carry weight nobody else wanted.
I focused on work.
A local startup hired me for a branding overhaul.
I spent long nights building campaigns and revising graphics, and the project led to a bonus and another referral.
My account began to stabilize after the move.
I slept better.
I even started imagining that leaving might actually be enough.
Three weeks after I moved out, my banking app sent me a notification.
I opened it casually.
Then stopped.
My savings balance was $10,000.
It had been $30,000.
I searched the transactions.
There it was.
A $20,000 withdrawal dated the day of Chelsea’s birthday.
I called the bank immediately.
The representative reviewed the account.
Then she explained that my mother had authorized the transfer.
Years earlier, Pamela had been given access when we created a joint emergency account.
I had forgotten she still had it.
“Where did the money go?” I asked.
The answer was a car dealership.
Chelsea’s dealership.
My savings had helped pay for the Tesla.
I sat in my little apartment staring at the statement.
The mortgage bill had been insulting.
This was different.
That $20,000 was money I had earned.
Money I thought was mine.
I emailed Dad and attached the bank record.
How could you let this happen?
His answer arrived a few hours later.
It was for the family’s image. You’re doing fine, aren’t you?
I read that sentence several times.
For the first time, I understood that my parents hadn’t merely assumed I would help them.
They had already helped themselves.
IF FACEBOOK BROUGHT YOU HERE, THEN THIS IS THE NEXT PART YOU’VE BEEN WAITING FOR. HAPPY READING!
The next day, Isaac found me at work staring at my computer.
He was a colleague around my age, practical and easygoing, and he noticed immediately that something was wrong.
He set a coffee beside me.
“You okay?”
I hesitated.
Then I told him.
The Tesla.
The $20,000 transfer.
Dad’s email about the “family’s image.”
Isaac’s expression hardened.
“That’s low.”
“I’ve thought about confronting them.”
“You could.”
I shook my head.
“They’ll just explain why I’m wrong.”
Isaac leaned against the desk.
“Then don’t let them decide what happens next.”
That advice stayed with me.
I did look into recovering the money.
I read about joint-account rules and spoke with a lawyer friend from college.
Her answer was disappointing but straightforward.
Because Mom still had legal access to the account, recovering the money through litigation could become expensive and complicated, potentially costing more than I would get back.
I closed that account.
Then I stopped treating the $20,000 as something my family could fix.
If it was going to be rebuilt, I would rebuild it.
A restaurant chain in Tulsa hired me for a marketing overhaul.
I worked late on ad concepts, branding, and social strategy.
The campaign performed well and gave me steadier income.
Then my friend Lindsey showed up one rainy evening carrying fried rice and spring rolls.
She sat on my secondhand couch and finally said:
“Your family wants you to come back.”
“They don’t want me back.”
She waited.
“They want their problem solver back.”
I told her about the bank statement.
Lindsey’s chopsticks stopped halfway to her mouth.
“Your mom took twenty thousand dollars?”
“To help pay for Chelsea’s car.”
She stared at me.
“I didn’t know that.”
“Most people don’t.”
Then Lindsey told me Dad was struggling badly and had left his job under stress.
“They’re in trouble.”
“They chose this.”
She didn’t argue.
Before leaving, she took another envelope from her bag.
“Your mom asked me to give you this.”
I recognized the handwriting.
I dropped it into the trash unopened.
Lindsey hugged me and left without pushing further.
For once, somebody accepted that I had reached my limit.
Around that time, I started planning something of my own.
A marketing company.
Small at first.
Local clients.
Isaac encouraged me to focus on niche businesses instead of trying to compete with giant agencies.
For the first time, my work wasn’t simply a way to recover from my family.
It was becoming a future.
Then Chelsea made everything public.
About a month later, my phone filled with notifications.
A friend messaged:
What’s going on with you and Chelsea?
I opened social media.
Chelsea had posted a long message saying I had selfishly abandoned the family when they needed me most.
People we had known growing up were commenting.
Some called me cold.
Others said family should come before money.
None of them knew about the mortgage bill.
None knew about the $20,000 taken from my savings.
I almost responded publicly.
I wanted to post the bank statement.
I wanted to tell everyone exactly where the Tesla money came from.
Instead, I closed the app.
Then an email from Mom arrived.
They had sold Chelsea’s Tesla to cover part of their debts.
If you hadn’t left, we wouldn’t be in this mess.
That was her conclusion.
Not that buying a $95,000 car while carrying serious mortgage debt had been a mistake.
Not that taking my savings had crossed a line.
I had caused the problem by refusing to keep absorbing it.
I finally called Chelsea.
“Take the post down.”
She laughed.
“You’re jealous.”
I hung up.
There was no useful conversation to be had.
Later that night, Dad texted.
We’re losing the house. The mortgage is too much. We need you.
For several minutes, I stared at those words.
The old instinct was still there.
Go back.
Fix it.
Make sure everyone is okay.
But every time I imagined returning, I saw that mortgage bill sliding across the birthday table.
Then I saw the $20,000 withdrawal.
I didn’t respond.
The next morning, I had one of the most important meetings of my career.
A Tulsa hotel chain was looking for a major marketing partner.
I presented my campaign.
That afternoon, they offered me a six-figure contract.
I signed.
That contract gave my fledgling firm room to grow.
By spring, I was working with the hotel group, boutique businesses, and a local tech startup preparing for a national rebrand.
Isaac continued helping me sharpen the business strategy.
Eventually, I moved from my cramped studio into a larger one-bedroom apartment downtown.
Floor-to-ceiling windows.
A sturdy desk.
A comfortable couch.
A few plants.
Nothing extravagant.
But every item in that apartment had been paid for without somebody reaching into my account.
Then Lindsey called.
“Your parents lost the house.”
I leaned against the kitchen counter.
I had expected it.
Still, hearing it felt different.
“They couldn’t keep up with the mortgage,” she continued. “Chelsea moved out of state.”
“I’m sorry they’re struggling.”
Lindsey was quiet.
Then she said, “I know.”
Mom contacted me later from a different number.
“We need you,” she said in a voicemail. “Everything is falling apart.”
I listened once.
Then deleted it.
They had needed me before.
The problem was that “need” had slowly become entitlement.
The same people who expected me to assume $60,000 of their mortgage debt had also taken $20,000 from my savings to maintain Chelsea’s image.
Helping them again wouldn’t undo that pattern.
It would restore it.
My business kept growing.
The hotel contract led to other opportunities.
The technology client opened more doors.
Eventually, I hired a small team.
Isaac arranged a modest celebration at a downtown bar after one particularly successful project.
He raised his glass.
“To the woman who doesn’t quit.”
People cheered.
I smiled because that recognition felt different from anything I had spent years chasing from my parents.
Nobody needed me to pay their mortgage first.
Six months later, I stood in the office of my own marketing firm looking over Tulsa.
My savings had recovered.
My client list had grown from local companies to national brands.
An old acquaintance told me my parents were living in a small apartment on the edge of town.
Chelsea was taking odd jobs in another state.
I didn’t enjoy hearing that.
I also didn’t feel responsible for correcting it.
My family continued telling people that I had abandoned them.
For a long time, that accusation bothered me.
Then I looked more carefully at what “abandonment” meant in their version of events.
I stopped paying their debts.
I stopped allowing access to my money.
I stopped accepting the idea that my responsibility was limitless because Chelsea’s wasn’t.
That wasn’t abandonment.
It was a boundary they had never expected me to have.
I still think about the birthday sometimes.
Not the Tesla itself.
The envelope.
That plain piece of paper containing a $60,000 mortgage bill while everyone outside was admiring Chelsea’s new car.
For years, I had believed being the reliable daughter would eventually make my parents value me differently.
Instead, reliability became something they budgeted around.
My income.
My savings.
My patience.
They assumed all three would remain available.
What finally changed my life wasn’t proving that Chelsea didn’t deserve the Tesla or proving that I deserved more.
It was realizing I didn’t have to participate in the comparison anymore.
I built a company.
I built my savings again.
I built a home that felt peaceful.
And I did it without waiting for my parents to admit they had been wrong.
The $20,000 never came back.
Neither did the old version of my family.
Some losses don’t get repaired.
You simply stop letting them determine the next decision.
The last time I stood looking over Tulsa from my office, I thought about the $30,000 I had once believed represented my entire future.
Twenty thousand disappeared in one transaction.
At the time, I thought my family had taken almost everything I had.
They hadn’t.
They took money.
They damaged trust.
They cost me years of believing that if I worked hard enough, gave enough, and asked for little enough, I would eventually be treated like Chelsea.
What remained was the part that mattered most.
I still knew how to work.
I still knew how to build.
And once I stopped using those abilities to support people who took them for granted, I finally had enough energy to build something for myself.
THE END. I’ve shared the complete story, and I truly hope it touched your heart. If this story moved you, please leave a comment, like, and share the post. Thank you for reading!